SCF Debt Figures: Check Who Is in the Median Before Comparing Yourself
Use a fictional ten-family exercise to see why debt-holder medians and all-family averages answer different questions, then learn how to read an SCF table.
A debt median is meaningful only after you know who is included. “Among families with this debt” answers a different question from “among all families.” Removing zero balances can change the middle value even though nobody’s debt changes.
Before comparing a headline with your own balance, identify its group, statistic and date. This guide shows why that check matters, using an invented exercise followed by a separate official table example. A survey comparison is not a recommended debt level.
Start with ten invented families
Imagine a complete population of ten families, each counted equally. These are fictional balances for one debt category at one snapshot, in a common dollar basis. They are not SCF observations. A zero means no balance in this category, not freedom from every kind of debt.
| Family position | Balance |
|---|---|
| 1 | $0 |
| 2 | $0 |
| 3 | $0 |
| 4 | $0 |
| 5 | $0 |
| 6 | $0 |
| 7 | $1,000 |
| 8 | $3,000 |
| 9 | $8,000 |
| 10 | $28,000 |
The balances add to $40,000. Four of the ten families have positive balances, so the holding share is 40%.
Calculate the middle twice
For all ten families, the middle positions are fifth and sixth. Both are zero, so the median is $0. The mean, or arithmetic average, is $40,000 divided by ten: $4,000.
Now ask only about families holding this debt. Their sorted balances are $1,000, $3,000, $8,000 and $28,000. The middle two are $3,000 and $8,000; their midpoint is $5,500. The same $40,000 divided by four gives a $10,000 mean.
| Group | Families | Median | Mean |
|---|---|---|---|
| All families | 10 | $0 | $4,000 |
| Positive-balance holders | 4 | $5,500 | $10,000 |
No family in this exercise owes exactly $5,500. With an even number of observations, the median can fall between the two middle amounts. Nor does a $0 all-family median mean nobody has debt: four families do.
Two shortcuts that fail
First, “average” does not tell you the median. Change only the largest invented balance from $28,000 to $68,000. The all-family mean rises to $8,000 and the holder mean to $20,000. Both medians stay unchanged because the middle positions have not moved.
Second, a holding share cannot convert one median into another. In the original example, 40% multiplied by the $10,000 holder mean equals the $4,000 all-family mean. But 40% multiplied by the $5,500 holder median gives $2,200, not the actual $0 all-family median.
That mean relationship works here because every nonholder has a zero and the groups use consistent counting. It is not permission to reconstruct precise survey estimates from rounded published figures. If nobody holds the debt, the holder mean and median are undefined. Missing information must not be silently turned into a zero.
Read a real SCF row separately
The latest Survey of Consumer Finances (SCF) is the 2025 survey, released October 9, 2026. Historical tables have nominal and inflation-adjusted versions; summary extracts use 2025 dollars. Federal Reserve SCF release and data.
In Table 4 of the Federal Reserve’s report, printed page 25, the 2025 credit-card-balances row reads as follows. Dollar entries are in thousands of 2025 dollars.
| Measure | Value | Comparison group |
|---|---|---|
| Share holding | 44.7% | All families |
| Median balance | $3,100 | Families holding this debt |
| Mean balance | $8,000 | Families holding this debt |
Here, a family is the primary economic unit: an economically dominant person or couple and financially interdependent household members, not necessarily every resident. Credit-card balances exclude purchases since the latest bill payment. Debts generally describe interview-time positions; income refers to the preceding calendar year. The report generally adjusts dollars to 2025 using CPI-U-RS. Table 4 and definitions, pages 25 and 39–45.
Keep this official row separate from the invented exercise. The share and balance statistics answer different questions. Neither balance statistic tells you how much debt is affordable for a particular family, or establishes a repayment target.
Why the classroom arithmetic is not a survey estimator
Our exercise has ten equally counted families and no missing values. Working with actual survey records requires more than sorting a spreadsheet.
The 2025 codebook identifies X42001 as the estimation weight. Weighting addresses unequal selection probabilities and nonresponse; unweighted record counts are not population shares. 2025 SCF codebook.
Five imputed records represent each family, not five independent families. Uncertainty calculations must account for sampling and imputation, using the applicable replicate-weight and implicate-combining guidance. SCF standard-error guidance.
This guide calculates no SCF microdata estimates and makes no statistical-significance claims. Its arithmetic checks validate only the fictional exercise.
Repair the headline before using it
Consider this deliberately fictional headline: “The typical family owes $10,000.” For our exercise, a precise replacement is: “Families with a positive balance average $10,000; the middle balance across all ten families is $0.”
When saving a real figure, use this extraction checklist:
- Which debt category and definition?
- Which family or household unit?
- All families, or only holders?
- Mean, median or holding share?
- Which survey year, release date and observation period?
- Which dollar multiplier and inflation basis?
- Which weighting and uncertainty limitations?
If a headline omits those labels, find the underlying table before treating its number as a useful comparison.
Mortgage Quote vs. Freddie Mac’s Average: Five Checks
Work through an invented mortgage quote with five record checks. Track what is known, what is missing and what to ask for in writing.
Invoice vs. Bank Payments: Find a $1,000 Double Count
Follow a fictional refrigerator invoice through six bank payments. A complete register and a two-month checkpoint reveal exactly how an incorrect $14,200 total duplicates…
Home-Sales Headlines: Read the Signing and Closing Calendars
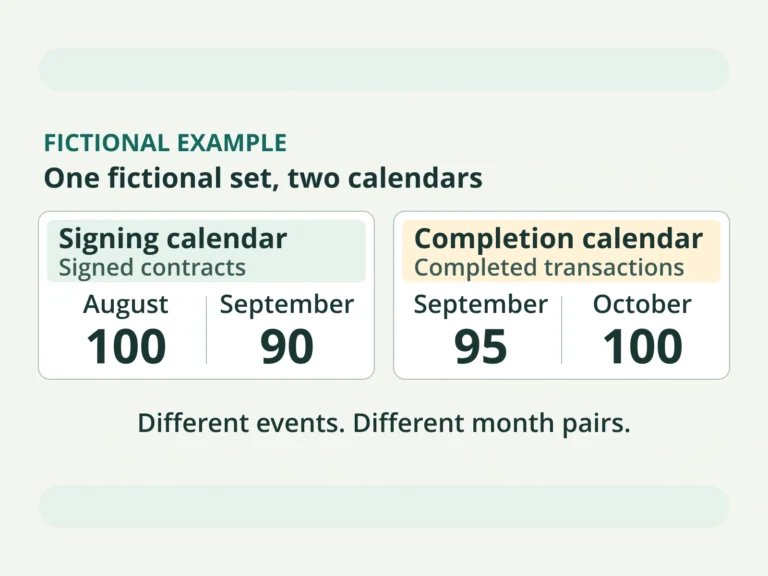
Follow 210 fictional home contracts across signing and closing months, then check which event and comparison base a housing headline actually uses.