Partnership Income
A partnership tax allocation, a distribution record and mortgage-income evidence answer different questions.
Estimated reading time: 2 minutes
A partnership tax allocation, a distribution record and mortgage-income evidence answer different questions.
Read what the tax form reports
The 2025 IRS partner instructions explain that Schedule K-1 reports a partner’s share of income, deductions and credits. A partner may owe tax on allocated income even when it was not distributed.
Box 19 needs its code and accompanying information. Code A can include cash and certain marketable securities; it is not simply a bank-deposit total. Do not label the entire entry as cash received without checking its composition.
Preserve the lender’s alternative evidence paths
Fannie Mae’s partnership guidance, dated February 7, 2024, requires documentation verifying either actual distributions consistent with the business income reflected on Schedule K-1, or adequate business liquidity to support withdrawing earnings.
Conversely, a tax allocation alone does not establish usable mortgage income. The lender selects an appropriate liquidity method; this is one consideration, not the entire qualification analysis.
For a borrower with at least 25% ownership when business returns are required, that guidance also requires business cash-flow analysis and evaluation of income stability and positive sales and earnings trends.
Keep the K-1’s allocated income, distribution composition and lender’s requested evidence separate. This comparison calculates neither tax nor qualifying income.
HELOC Balances and Mortgage Ratios
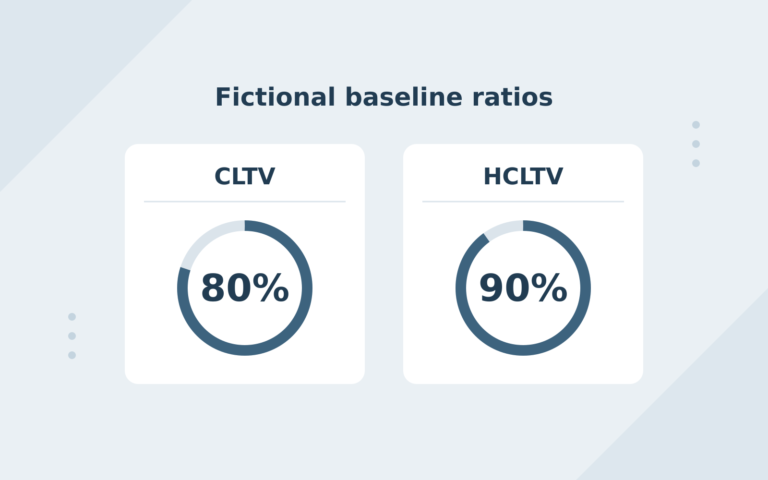
Compare drawn balances with committed credit.
Mortgage Payments Below Interest
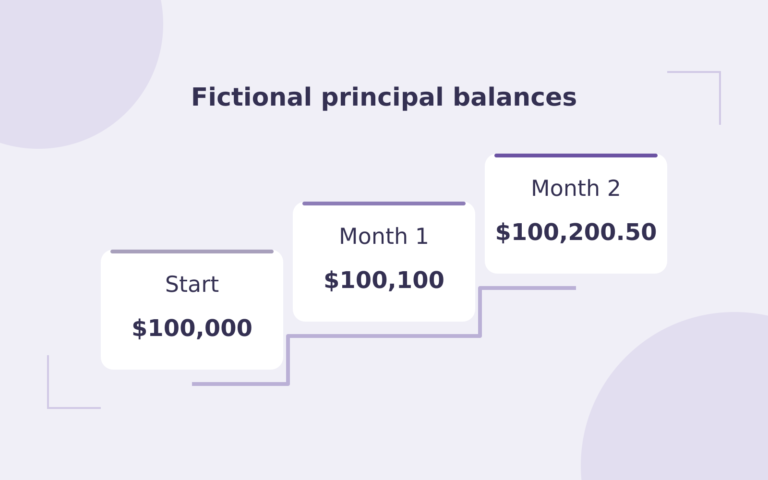
Trace cash paid and debt remaining.
Refinancing: Remaining Mortgage Points
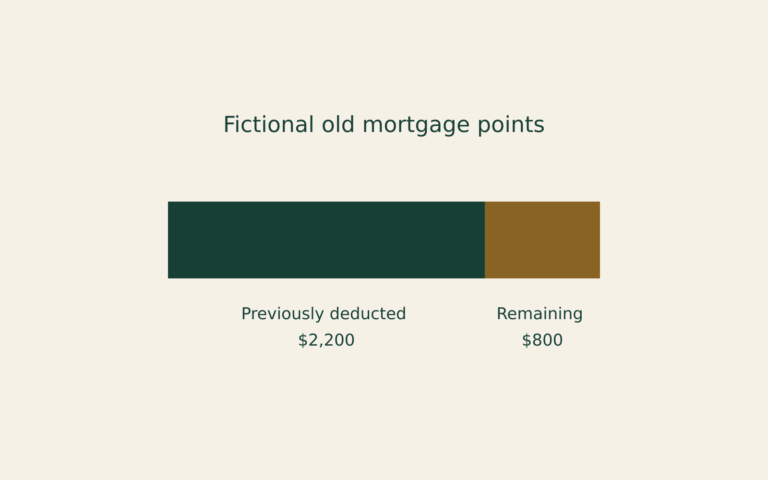
Track previously deducted and remaining points.