Refinancing: Remaining Mortgage Points
Track previously deducted and remaining points.
Estimated reading time: 1 minute
A mortgage payoff does not always make all undeducted points immediately deductible.
Carry forward the old ledger
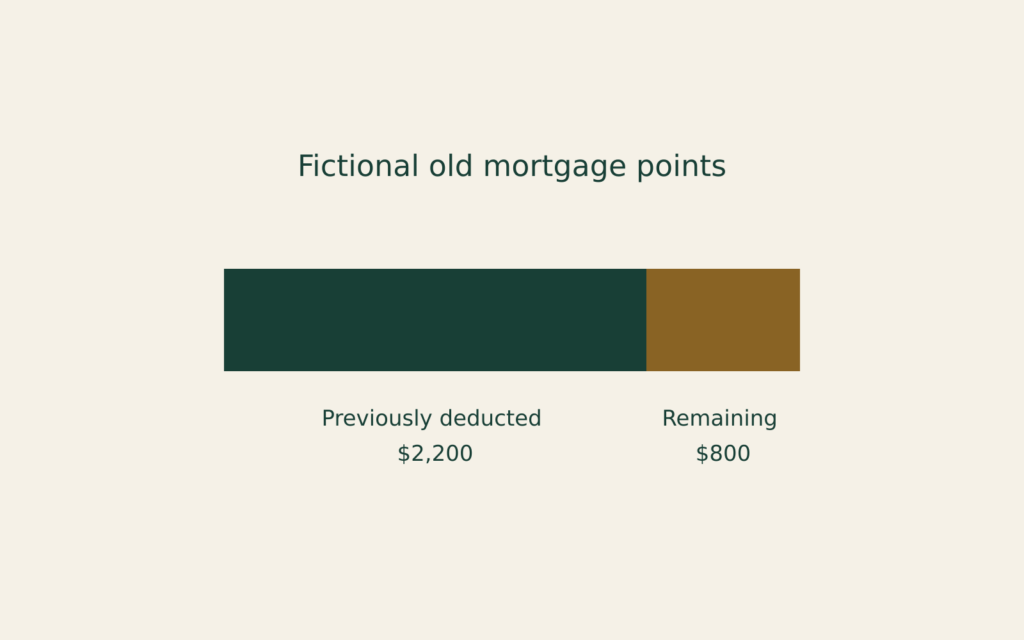
Consider alternative fictional 2025 refinancings of a mortgage secured by the taxpayer’s main home. The taxpayer itemizes; both loans are qualifying acquisition debt within applicable deduction limits. The old mortgage’s $3,000 of qualifying points had to be deducted over its term. Correct prior deductions total $2,200, leaving $800. There are no new points, refunds or other adjustments.
A: A different lender refinances and fully terminates the old mortgage. The remaining $800 is deductible in the termination year.
B: The same lender refinances. The $800 is instead deducted over the new loan’s term, not all immediately because the old balance was paid.
IRS Publication 936 (2025) describes this distinction. Match original qualifying points, prior deductions, payoff and actual lender identity. The $800 is neither a refund nor tax savings; no new amortization schedule or refinancing recommendation is provided.
HELOC Balances and Mortgage Ratios
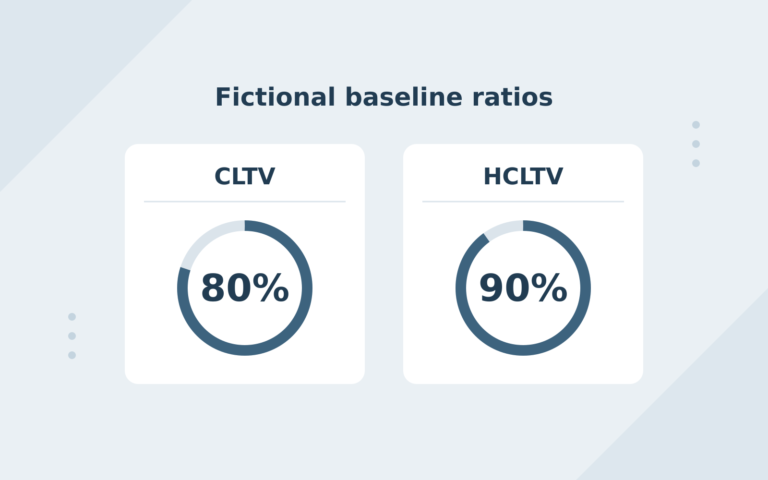
Compare drawn balances with committed credit.
Mortgage Payments Below Interest
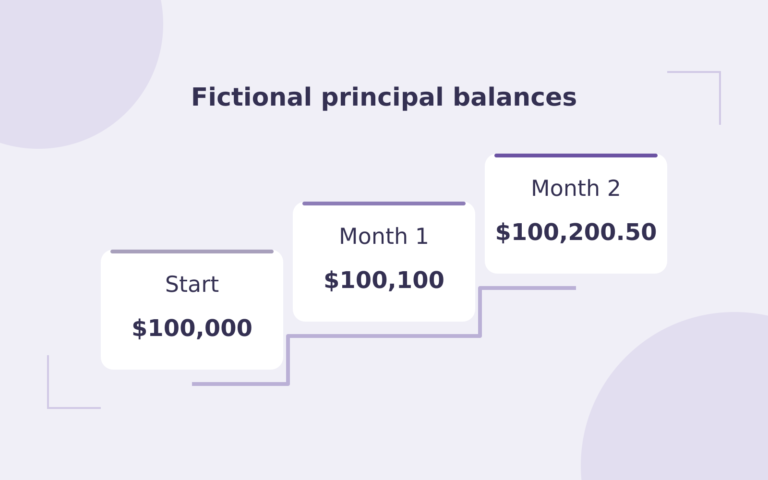
Trace cash paid and debt remaining.
Cash-Out Refinancing: Which Debt Qualifies as Home Acquisition Debt?
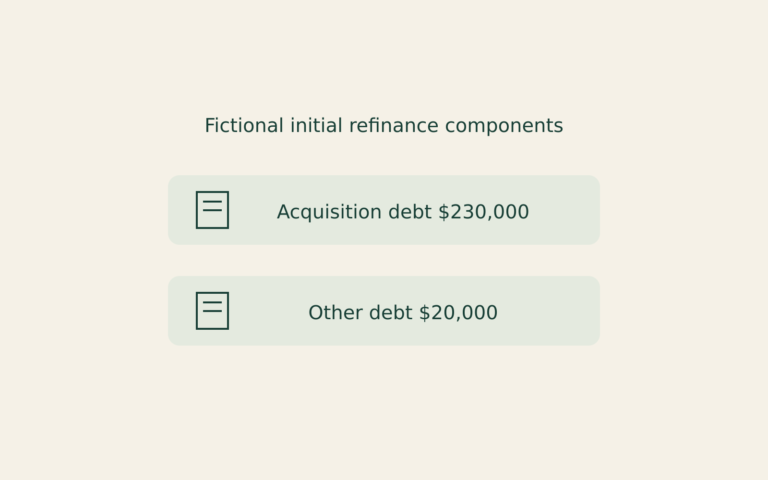
Trace a fictional refinance to the old principal, qualifying home improvements and personal spending before deciding what the debt classification shows.