Lease Payment Components
Separate depreciation and rent calculations.
Estimated reading time: 1 minute
The Minnesota Attorney General’s leasing guide describes a payment method using two different bases. Confirm your lessor uses it; formulas vary.
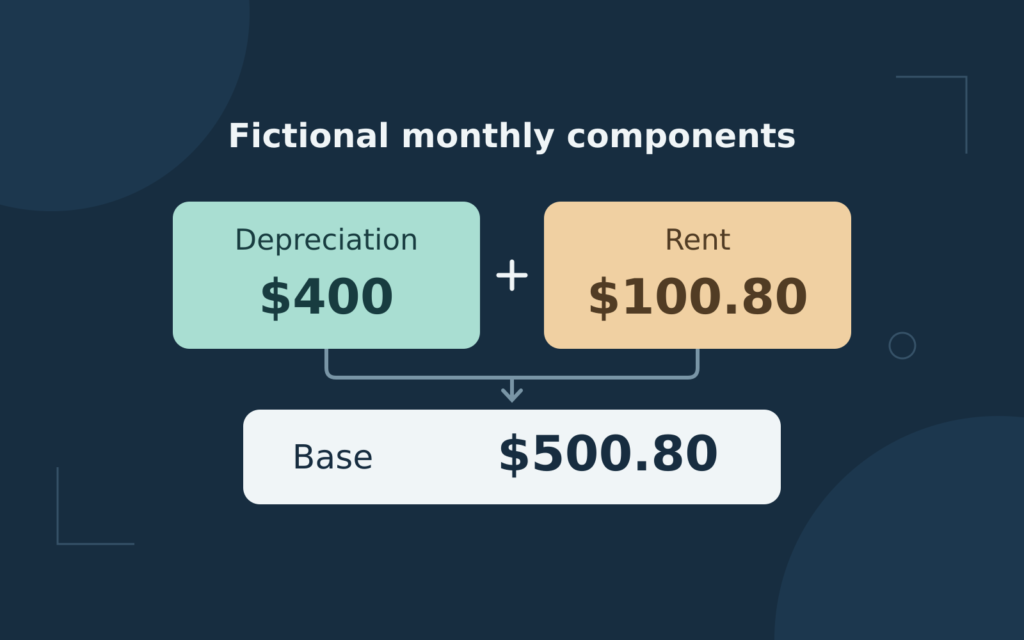
Fictional inputs: $32,400 adjusted capitalized cost, $18,000 residual, 36 monthly payments and a 0.002 money factor. These are supplied figures, not current offers. Taxes, fees and other charges are excluded.
Monthly depreciation uses the difference: ($32,400 − $18,000) ÷ 36 = $400. Monthly rent uses the sum: ($32,400 + $18,000) × 0.002 = $100.80. Base payment is $500.80.
Applying the factor only to the $14,400 depreciation amount gives $28.80 rent, understating the monthly payment by $72.
For a separate comparison, change only residual to $21,600. Depreciation becomes $300; rent becomes $108; base payment becomes $408. The payment falls $92.80, not $100, because rent rises $7.20.
Residual is a calculation input, not guaranteed resale proceeds. Neither base payment is the total cost of leasing. Obtain the complete signing, payment and end-of-lease charges before comparing actual offers.
Dental Plans and Non-Duplication
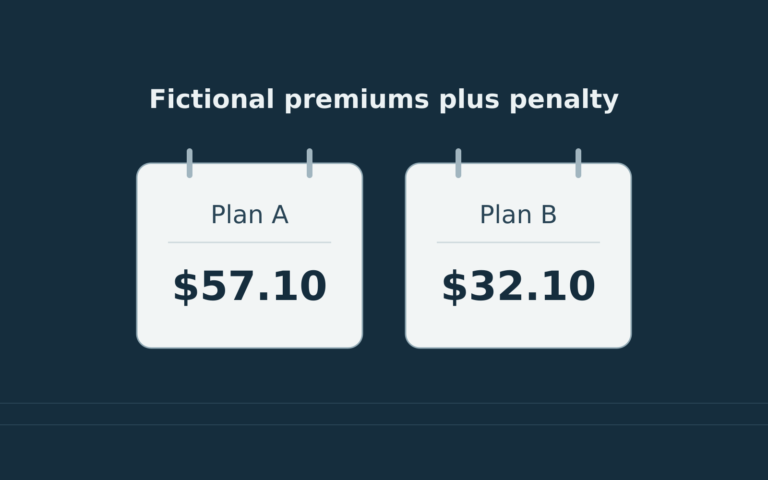
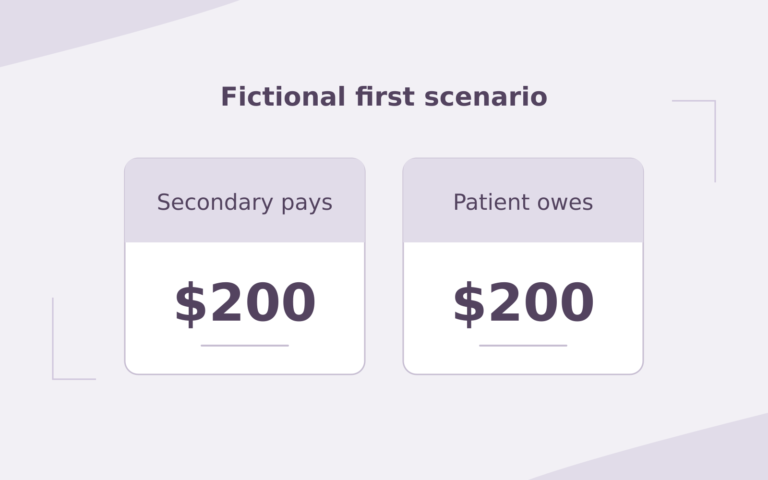
Calculate the secondary payment.
Rent-to-Own: Remaining Purchase Costs
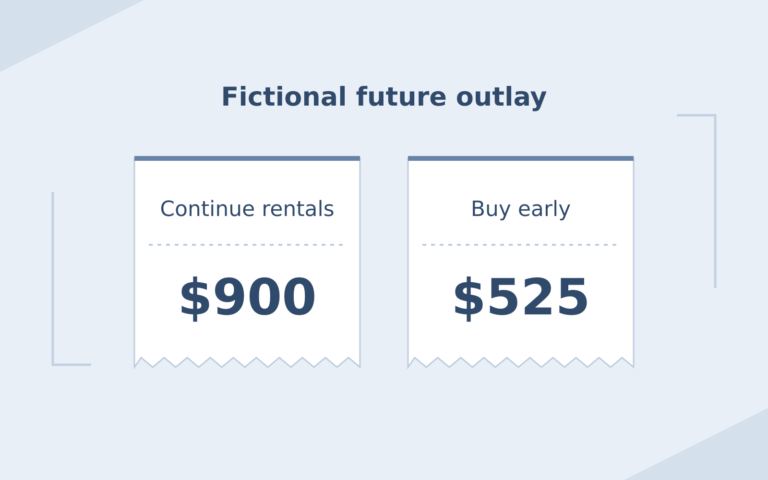
Compare future outlay and available cash.