Mortgage Payments Below Interest
Trace cash paid and debt remaining.
Estimated reading time: 1 minute
The CFPB describes mortgage payment options that can leave interest unpaid and added to principal. A permitted minimum payment need not reduce debt.
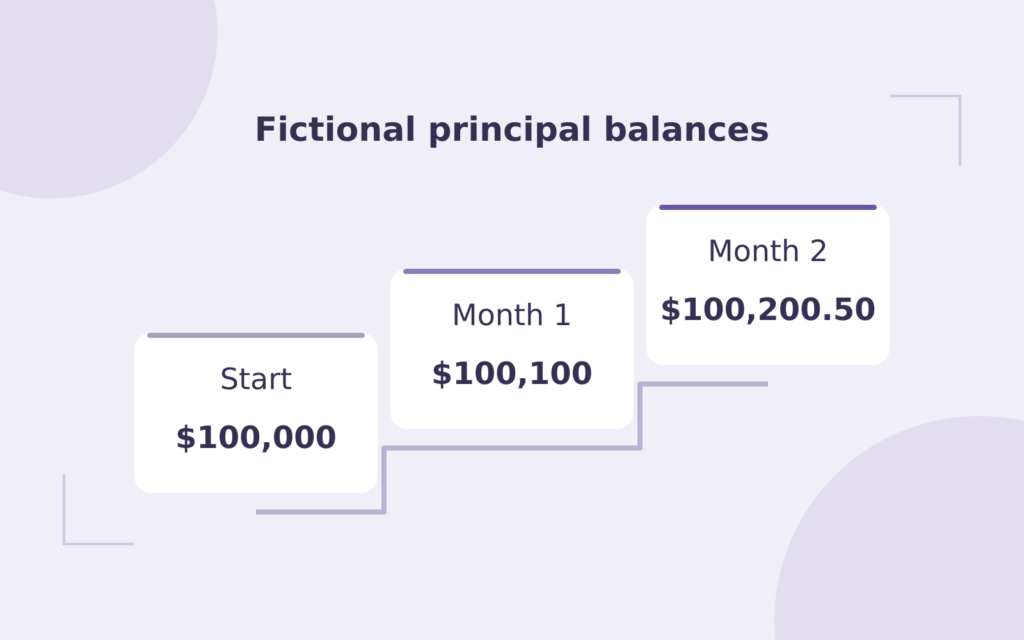
Fictional two-month example: $100,000 opening principal, 0.5% monthly interest and $400 month-end payments. Assume the contract permits these payments and adds unpaid interest monthly. No fees, escrow, rate changes or other adjustments.
Month one: $100,000 × 0.005 = $500 interest. Paying $400 leaves $100 added to principal: $100,100.
Month two: $100,100 × 0.005 = $500.50 interest. Another $400 payment leaves principal at $100,200.50.
Alternatively, paying $500 interest each month keeps principal at $100,000. The smaller payments retain $200 cash across both months but leave $200.50 more debt, not $200 saved.
The CFPB warns that later principal-and-interest payments can rise. Ask your servicer when recalculation occurs and what payment covers interest and reduces principal. These figures are not permission to underpay another contract.
Land Release and Mortgage Paydown
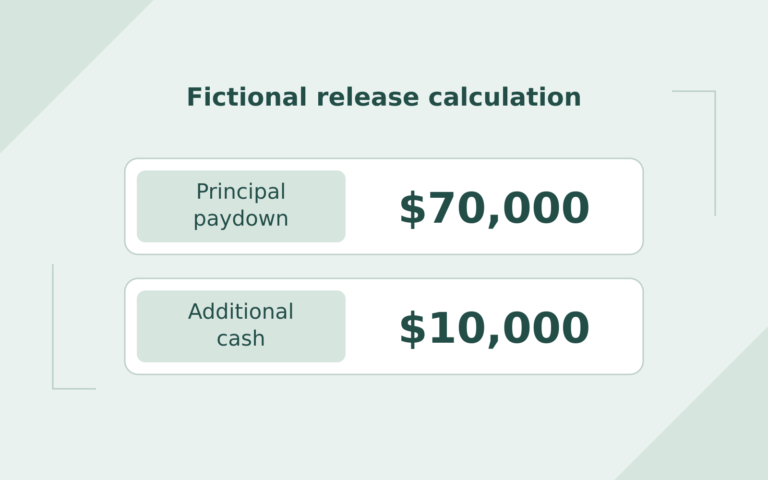
Compare proceeds with paydown.
Mortgage Fees: Aggregate Increases
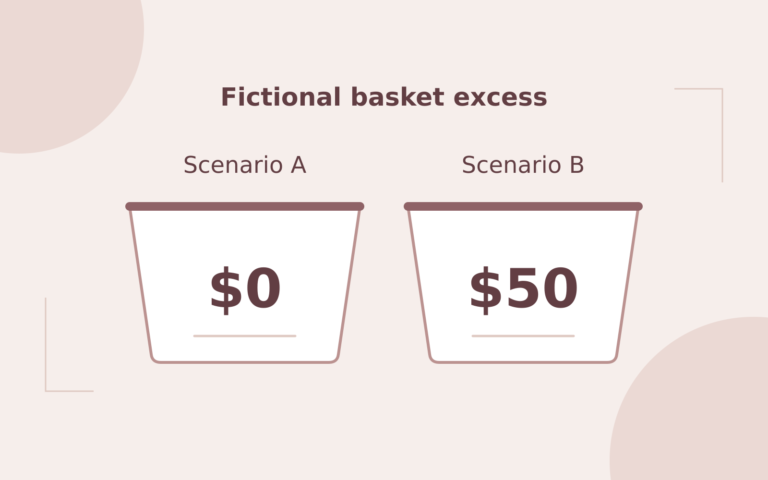
Compare the complete charge basket.
HELOC Balances and Mortgage Ratios
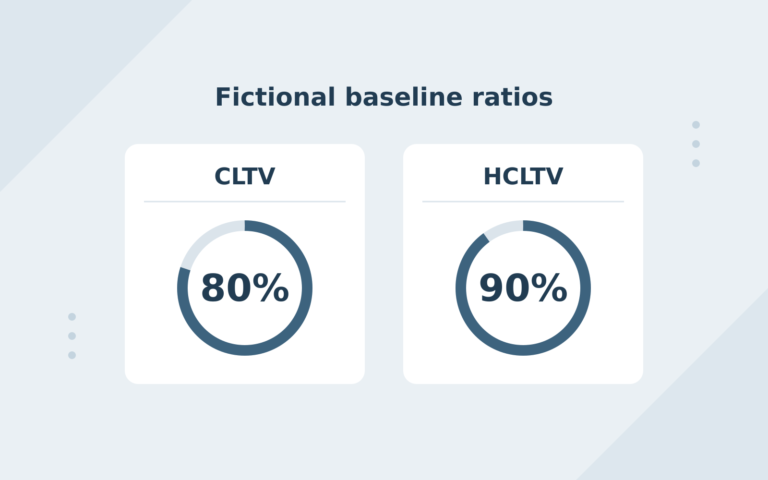
Compare drawn balances with committed credit.