Business and Owner Debt Coverage
Count distributions only once.
Estimated reading time: 1 minute
Commerce Bank describes combined business and personal debt coverage. FISCAL warns against counting owner distributions without deducting them from business cash flow.
Fictional annual model: business cash available before distributions and debt service is $120,000, after all other outflows. It distributes $40,000 to its sole owner.
The owner also receives $20,000 from outside the business and pays $30,000 of taxes and living costs, excluding debt payments. Assume no other entities, transfers or adjustments.
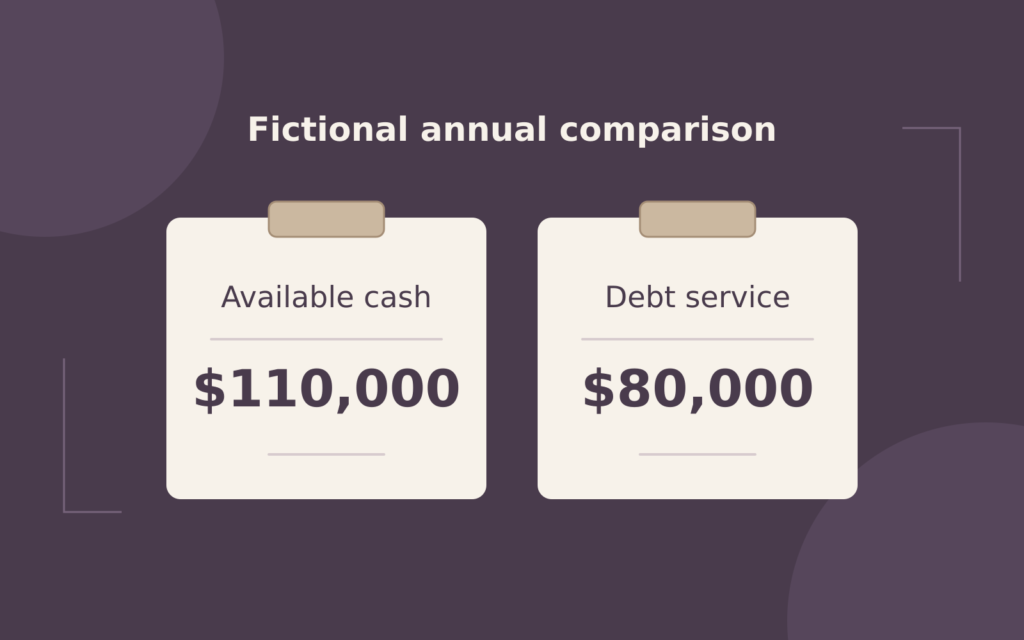
Business availability is $80,000. Personal cash available is $40,000 + $20,000 − $30,000 = $30,000. Combined availability is $110,000.
Annual principal and interest total $60,000 business plus $20,000 personal. The modeled coverage ratio is $110,000 ÷ $80,000 = 1.375.
Adding personal availability to the unreduced $120,000 would falsely produce $150,000 and 1.875 coverage. That counts the same distribution twice.
Ask the lender to reconcile transfers, included obligations and cash definitions. This annual arithmetic neither proves payment-date liquidity nor permits moving restricted funds. It is not a lender’s approval test.
Inventory Replenishment Quantities
Check outstanding commitments.