Salvage Retention and Cash
Separate property ownership.
Estimated reading time: 1 minute
Texas OPIC explains that keeping a totaled vehicle can reduce the claim payment by its salvage value. A retained car is not extra cash.
Fictional alternatives: an insurer confirms a $15,000 settlement before any retention deduction, already accounting for applicable deductible, taxes and fees. The lender’s same-date payoff is $13,000. Assume no other credits, charges or changes.
If the insurer takes the vehicle and pays the lender first, $15,000 minus $13,000 leaves $2,000 for the owner.
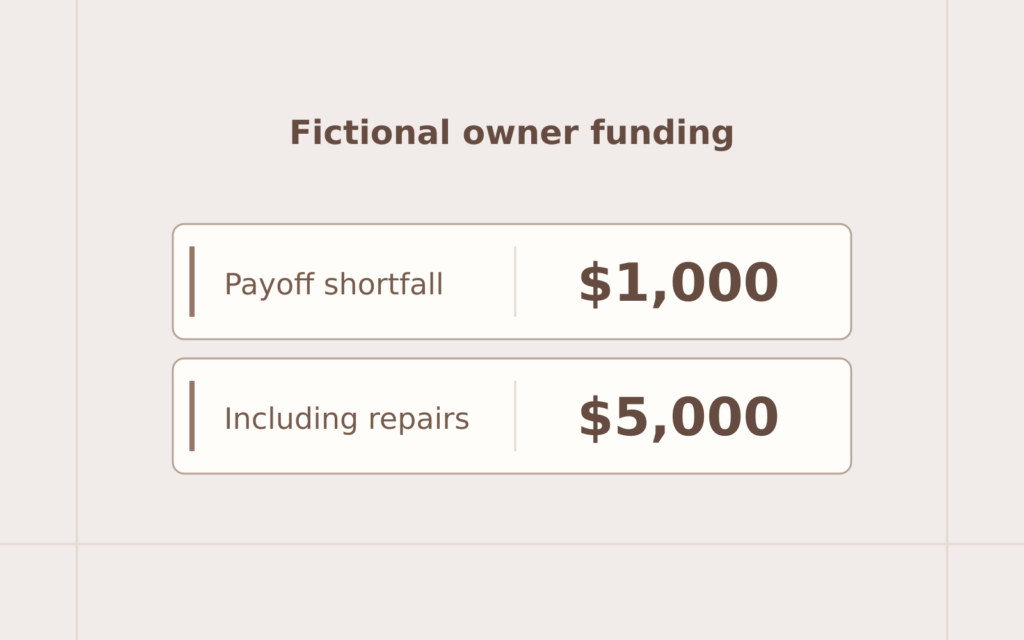
If both insurer and lender permit retention with a $3,000 salvage deduction, the payment falls to $12,000. The owner needs $1,000 more to complete the assumed payoff—not $2,000 of replacement-car cash.
Add a separate $4,000 repair estimate: retention needs $5,000 of owner funding in this model. The retained vehicle’s value does not pay those bills.
Ask for both written settlements, lender instructions and repair estimates. Repairs can uncover additional damage; Texas requires steps before returning a totaled vehicle to the road. These figures establish neither roadworthiness nor the better economic choice.