Mortgage Escrow Surplus Threshold
Compare surplus outcomes.
Estimated reading time: 1 minute
An escrow surplus is not the same as the full balance in your mortgage escrow account. Under Regulation X, a surplus is the amount above the target balance at the time of analysis.
Compare two separate analyses
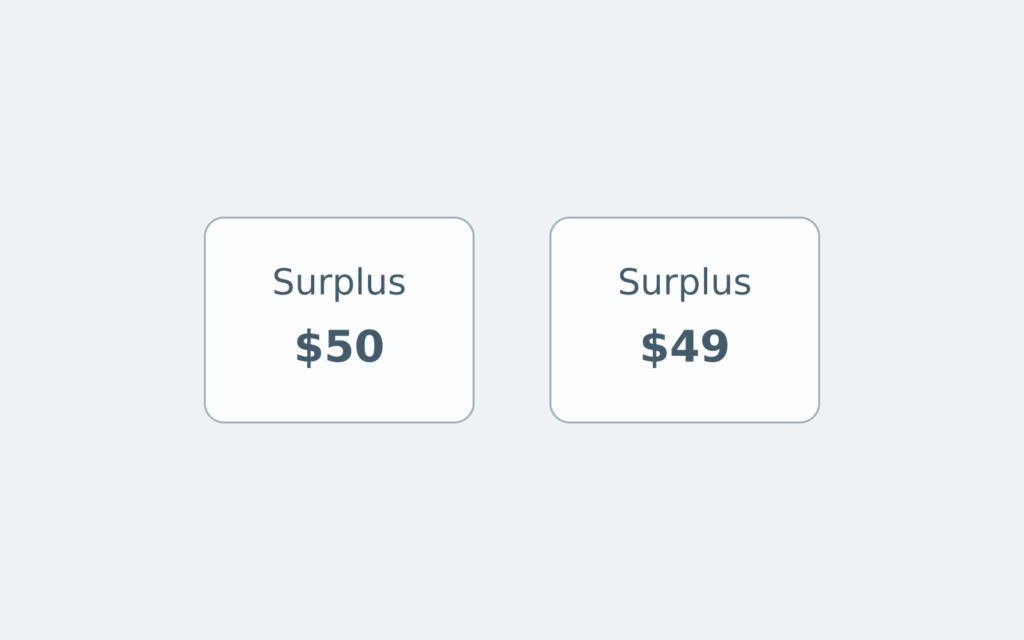
Assume a covered federally related mortgage and a borrower current at the analysis. Fictional alternatives:
- A $50 surplus: the servicer must refund the surplus within 30 days of the analysis.
- A $49 surplus: the servicer may refund it or credit it against the next year’s escrow payments.
The $1 difference crosses the $50 threshold. It does not mean $50 is deducted from either amount. The rule uses the analysis date, not the date the borrower reads the statement.
Check the account and dates
For this rule, current generally means the servicer receives payments within 30 days of their due dates. If that condition is not met, different treatment may apply under the loan documents. Keep the analysis, payment history and refund or credit record. A projected balance is not itself proof of cash received.

One Mortgage Form, Two Borrowers
Match each person’s share.