Compensation Per Worked Hour
Count leave once.
Estimated reading time: 1 minute
Employer cost per hour worked is not necessarily the employee’s hourly wage.
BLS defines this measure using employer compensation costs divided by hours worked, excluding leave hours from that denominator.
Use worked hours
Fictional annual budget: 2,000 paid hours at $25, including 200 hours of paid leave. Assume no overtime and $10,000 of additional employer benefits and payroll costs, excluding leave pay already counted.
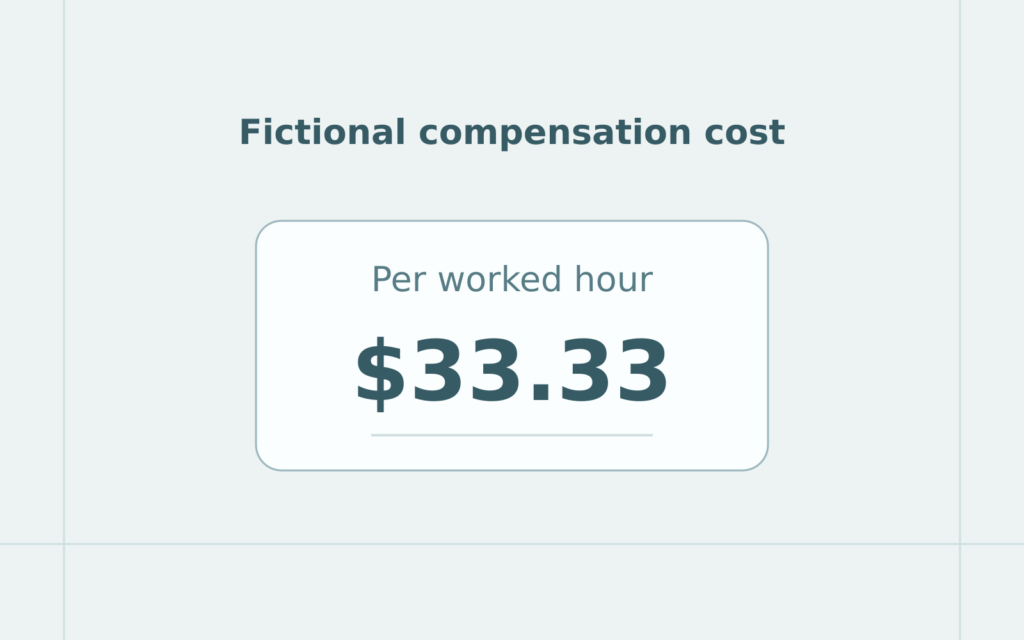
Wages and leave pay total $50,000. Combined compensation cost is $60,000. Hours actually worked are 2,000 − 200 = 1,800.
Cost per worked hour is $60,000 ÷ 1,800, approximately $33.33. Dividing by all 2,000 paid hours gives $30, which answers a different question.
Adding another $5,000 for the 200 leave hours would count that pay twice. Conversely, paying only 1,800 hours in the model would omit promised leave pay.
Match payroll, benefit costs and worked hours for the same period. This compensation-only illustration excludes business overhead and profit; it is neither a customer billing rate nor a calculation of employee take-home pay or legal entitlements.