Federal Progress Payments: Why a Delivery Invoice Can Bring Less Cash
Follow two fictional delivery payments as earlier federal contract financing is recovered through liquidation deductions.
Estimated reading time: 3 minutes
This guide concerns cost-based financing under a contract using FAR 52.232-16, not construction progress billing.
A federal delivery invoice can be larger than the cash still payable because earlier financing is being recovered. Identify any progress-payment liquidation before putting the invoice’s full amount into a cash forecast.
Financing and delivery payments are different entries
FAR 32.001 defines contract financing as authorized government disbursement before acceptance. Cost-based progress payments under FAR 52.232-16 are included. Delivery payments concern accepted supplies or services, including accepted partial deliveries.
In this setting, “liquidation” means reducing a payment to recoup financing already paid. It doesn’t mean the contractor is going out of business.
Use the contract’s liquidation provision
The basic FAR 52.232-16(b) provision deducts the lesser of remaining unliquidated progress payments and 80% of the invoiced amount, subject to its terms. This is a recovery percentage, not an interest rate.
Read the actual clause, alternates, modifications and agency deviations. The example assumes the basic 80% provision applies unchanged; it doesn’t establish financing eligibility or a universal federal rate.
Follow two invoices after $60,000 already arrived
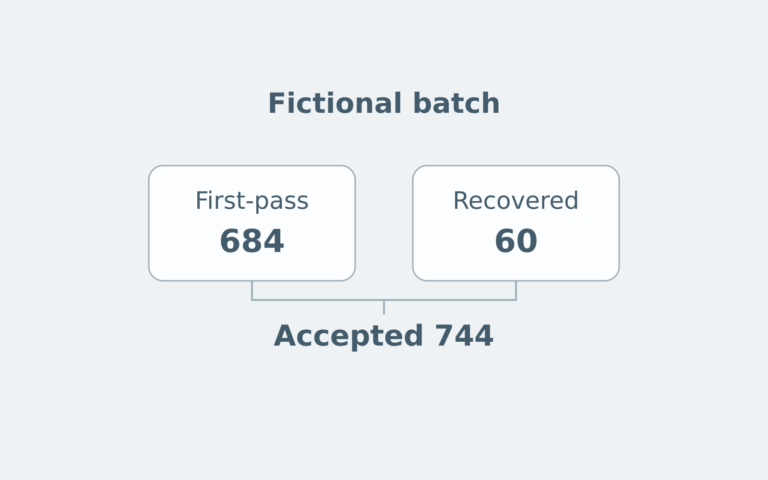
Original hypothetical: One $100,000 fixed-price supply contract has valid, approved cost-based progress financing. Before either delivery payment, $60,000 has been received and none liquidated. Assume all financing conditions remain satisfied, no further financing is paid, and two accepted deliveries are each invoiced at $50,000.
There are no price changes, disputes, assignments, other deductions, interest penalties or termination. All listed receipts are completed for this exercise. It isn’t a prediction of payment dates or permission to submit a request.
| Entry | First invoice | Second invoice |
|---|---|---|
| Gross invoice | $50,000 | $50,000 |
| Unliquidated financing before payment | $60,000 | $20,000 |
| 80% of invoice | $40,000 | $40,000 |
| Liquidation deduction: smaller amount | $40,000 | $20,000 |
| New delivery-payment cash | $10,000 | $30,000 |
| Unliquidated financing afterward | $20,000 | $0 |
Reconcile the whole receipt history
Completed cash totals $60,000 + $10,000 + $30,000 = $100,000. Adding the original $60,000 to both gross $50,000 invoices instead produces $160,000—overstating receipts by the $60,000 already recovered through deductions.
The first delivery’s $40,000 deduction isn’t another $40,000 cash payment from the contractor’s bank account in this ledger. Record its effect on the financing balance separately from the $10,000 deposit.
This is a receipt reconciliation, not profit or taxable-income accounting. No production costs, taxes, bank balances or payment dates are supplied. The earlier $60,000 may already have funded work; cumulative receipts don’t establish cash currently available for payroll.
Recheck the rate instead of extending the toy schedule
FAR 32.503-8 describes the ordinary method: liquidation uses the same rate as progress financing and is applied to delivered-and-accepted contract-item prices. That general method doesn’t replace the operative contract terms.
Ask the contracting and payment offices to explain the applied rate, starting unliquidated amount and any other adjustment. If the remittance differs from your worksheet, retain the unexplained difference rather than labeling every deduction a liquidation.
For separate questions, read invoice receipt, acceptance and payment timing or assignment of federal payment rights.
Primary sources checked October 28, 2026. Standard-clause educational example only; no contract action or individualized legal determination is supplied.