Foreign Income: Two Periods
Reconcile qualification and annual proration.
Estimated reading time: 1 minute
A qualifying 12-month presence period does not automatically provide a full calendar-year foreign-income exclusion.
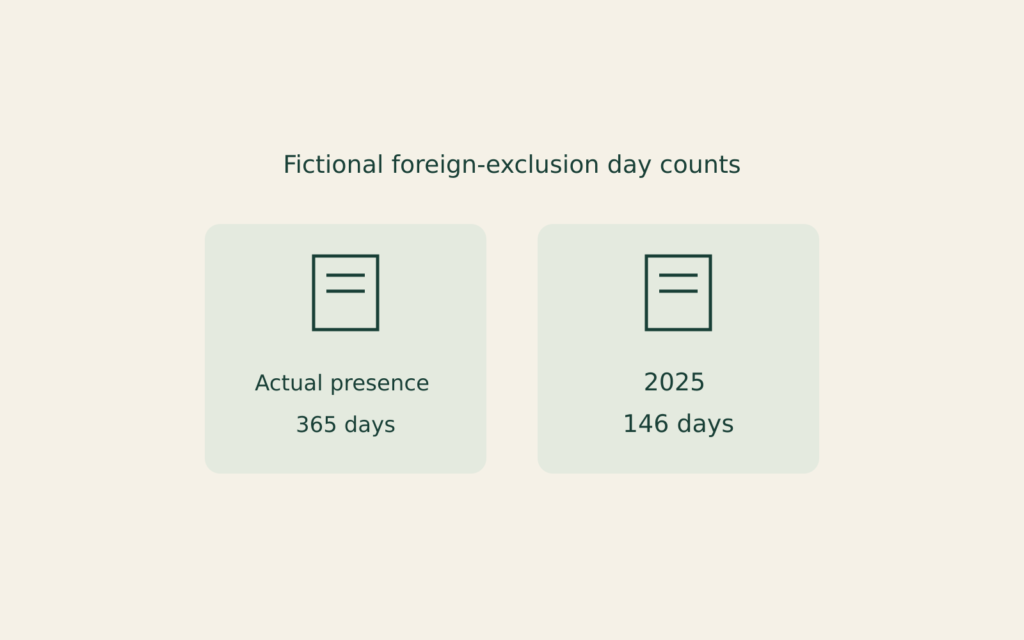
A fictional single U.S. citizen starts indefinite private employment in Germany on August 8, 2025. No earlier foreign qualifying period applies. Verified records show continuous full-day presence in Germany from August 8, 2025 through August 7, 2026: 365 days, exceeding the 330-day requirement. Throughout that period, Germany is their home and sole regular workplace; they have no U.S. abode.
They validly elect the exclusion. Their only 2025 foreign earned income is $60,000 salary earned and received for services performed there from August 8–December 31. There is no housing exclusion, allocable deduction or special adjustment.
2025 Form 2555 counts qualifying days within 2025 separately: August 8–December 31 is 146 days. The prorated limit is $130,000×(146÷365)=$52,000.
The exclusion is the smaller of $60,000 income and $52,000: $52,000, leaving $8,000 unexcluded—not $130,000 or the entire salary. This reconciles the two periods; it does not calculate final tax or recommend an election.
Social Security: Retroactive Benefit Tax
Compare two taxable-benefit calculations.
Home Office: Expense Deduction Order
Separate current and carried expenses.
Retirement Formula: From Indexed Total
Follow two rounding stages.