Insurance Gain and Replacement Basis
Reconcile replacement spending and postponed gain.
Estimated reading time: 1 minute
Replacing destroyed equipment does not necessarily postpone all insurance-related gain.
A fictional calendar-year U.S. sole proprietor’s separately accounted freestanding manufacturing machine is completely destroyed by an accidental fire in January 2025. Bought for $10,000 in 2022 and used exclusively in business, it has $6,000 verified depreciation, both allowed and allowable, and no other basis adjustments.
The owner receives $12,000 insurance in March. In April, they buy and use a $10,000 replacement machine from an unrelated seller, performing the same manufacturing function. No debts, expenses, other property or reimbursements apply. They validly elect postponement for this completed replacement.
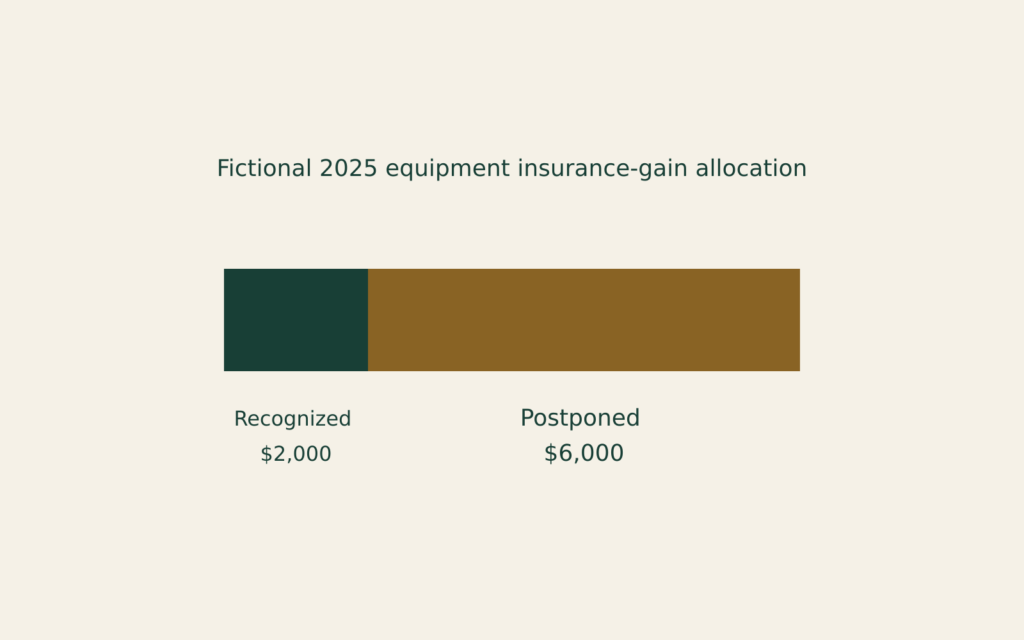
Under Publication 547, replacement spending below reimbursement leaves gain recognized up to the unspent amount. Basis is $4,000; realized gain is $12,000−$4,000=$8,000. Recognized gain is $2,000; postponed gain is $6,000.
Publication 544 limits ordinary depreciation recapture here to that $2,000. Replacement basis is $10,000−$6,000=$4,000, not its purchase price. This reconciles current recognition and replacement basis—not final tax or a recommendation to elect postponement.
Social Security: Retroactive Benefit Tax
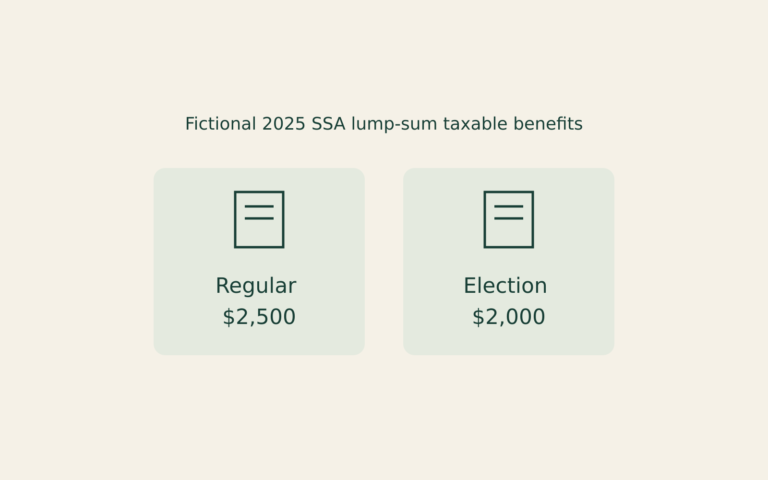
Compare two taxable-benefit calculations.
Home Office: Expense Deduction Order
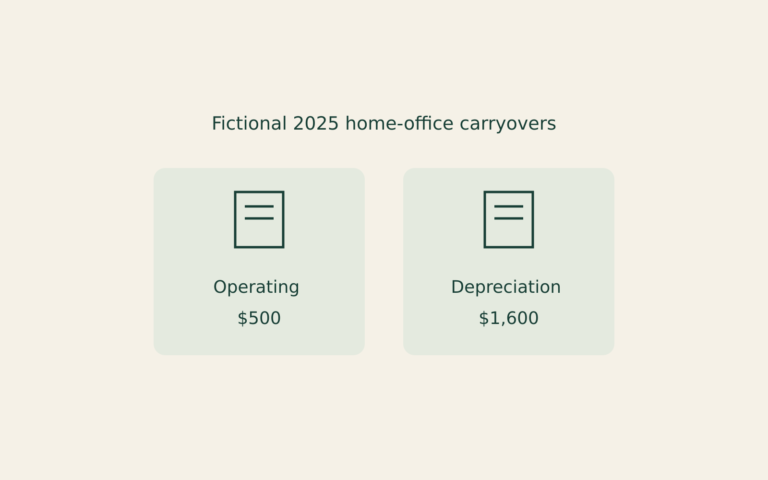
Separate current and carried expenses.
Retirement Formula: From Indexed Total
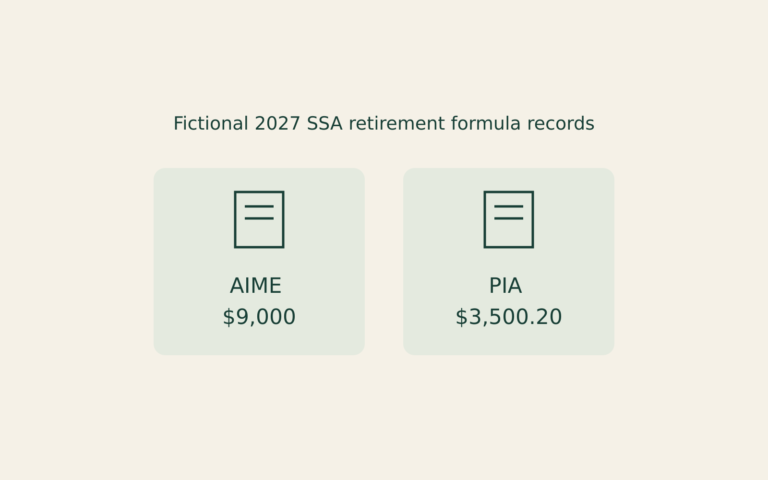
Follow two rounding stages.