Marketing Loan Benefit Routes
Compare financing and benefits.
Estimated reading time: 1 minute
USDA ERS explains two alternative marketing-loan benefits: reduced loan repayment or a direct loan deficiency payment without borrowing.
Fictional comparison: assume 10,000 eligible bushels, a $2 loan rate and an applicable $1.60 repayment rate per bushel. Eligibility and identical benefit-date rates are stipulated, not current quotations.
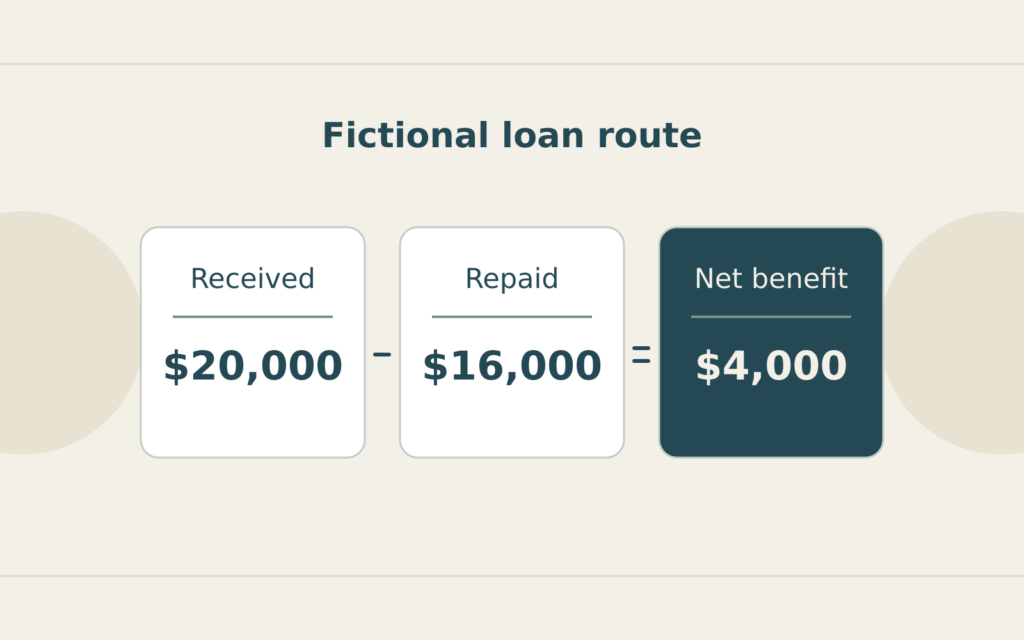
Loan route: receive $20,000 earlier, then repay $16,000. The $4,000 difference is the marketing loan gain. ERS says accrued interest is waived when repayment uses the lower rate.
Direct-payment route: without taking the loan, receive ($2 − $1.60) × 10,000 = $4,000. There is no $20,000 advance or $16,000 repayment.
Both routes yield $4,000 before excluded costs and taxes, but only the loan route supplies earlier financing and requires repayment cash. The gain is not another $4,000 deposit to add to its net cash.
These are alternatives, not benefits to stack on the same bushels. Ask FSA to confirm eligibility, deadlines, repayment terms and actual amounts before choosing. This comparison excludes crop sales, storage costs and other cash flows.
Construction Retainage and Cash
Reconcile the current payment.