Nontaxable Income and Qualification
Check the adjustment.
Estimated reading time: 1 minute
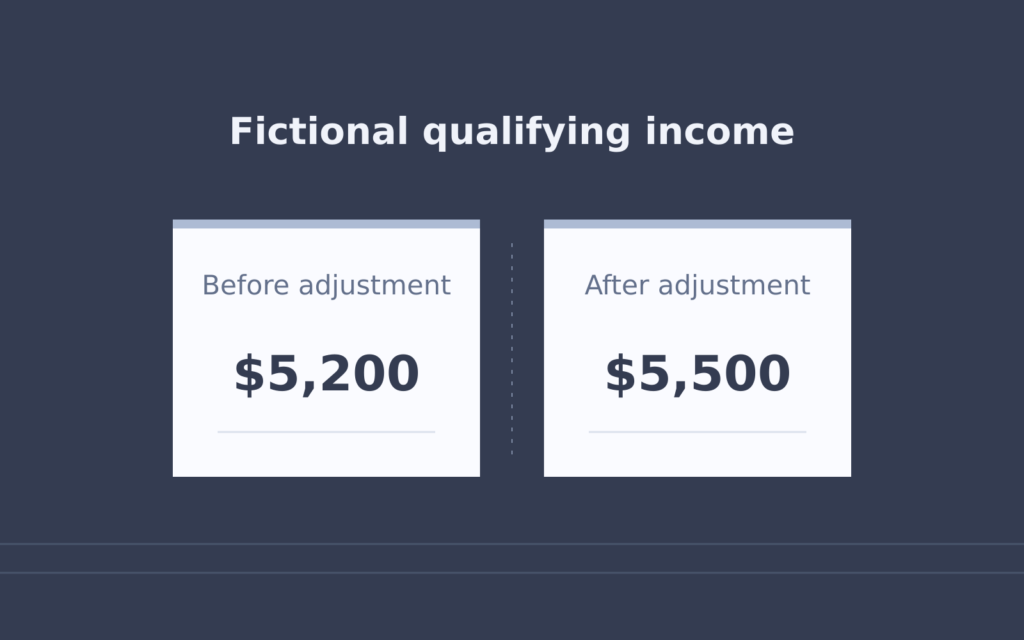
Fannie Mae’s income guide describes adding 25% of verified nontaxable income when that income and its tax-exempt status are likely to continue. This qualifying adjustment is not extra cash received.
Fictional monthly inputs: $4,000 taxable gross income and $1,200 nontaxable income. Assume the lender has verified eligibility, documentation and continuance, and uses the guide’s 25% method.
Add $1,200 × 25% = $300. Adjusted qualifying income is $4,000 + $1,200 + $300 = $5,500.
With $2,200 of confirmed monthly obligations, including housing, the ratio is $2,200 ÷ $5,500 = 40%. Without the adjustment, $2,200 ÷ $5,200 is approximately 42.31%.
Multiplying all $5,200 by 1.25 would incorrectly produce $6,500 income and approximately 33.85%. The taxable portion receives no addition.
The $300 adjustment creates neither a deposit nor a tax deduction. Build the spending budget from actual take-home receipts and expenses.
Ask the lender to identify the nontaxable portion and adjustment used. The guide permits a different adjustment when supported by higher comparable taxes. These calculations do not establish approval or affordability.
Land Release and Mortgage Paydown
Compare proceeds with paydown.