Room Revenue and Costs
Compare metrics.
Estimated reading time: 1 minute
CoStar’s STR glossary separates average daily rate (room revenue divided by rooms sold) from revenue per available room, or RevPAR. Neither deducts operating costs.
Keep the available-room denominator
Fictional hotel: 100 rooms available on each of two nights. Night A sells 80 rooms at $100 each: revenue $8,000, occupancy 80%, RevPAR $80. Night B sells 60 at $125: revenue $7,500, occupancy 60%, RevPAR $75.
The sold-room rate rises 25%, but RevPAR falls 6.25%. Dividing B’s revenue by its 60 sold rooms answers the rate question, not the available-room question.
Revenue is not profit
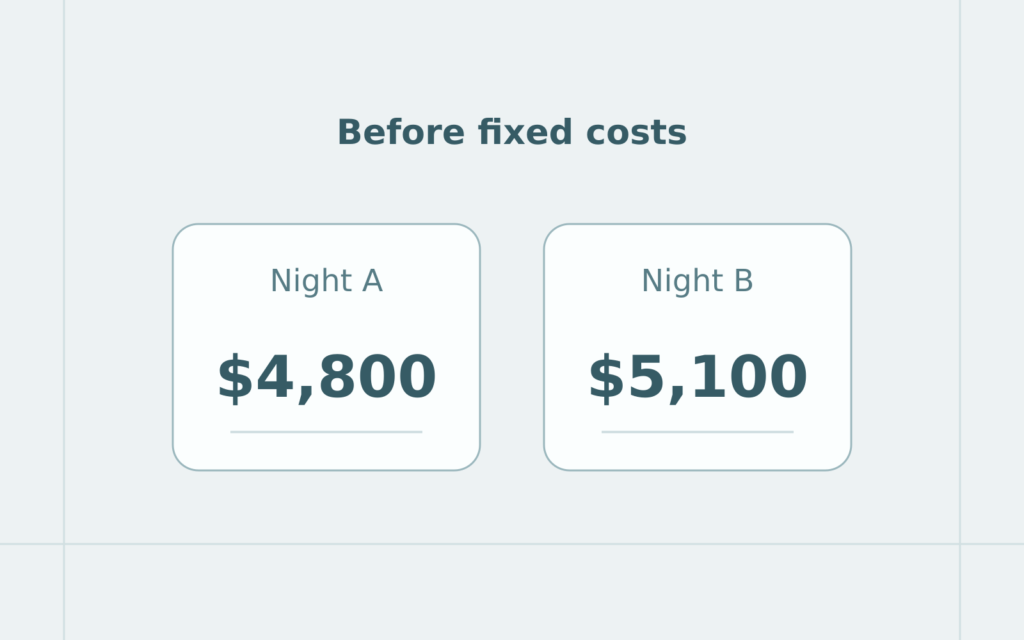
Now assume $40 in variable operating costs per occupied room, with no other variable costs. A leaves $8,000 − $3,200 = $4,800; B leaves $7,500 − $2,400 = $5,100 before fixed costs. The lower-revenue night leaves $300 more.
These are contributions, not net income. Fixed costs, financing, taxes and other revenues remain outside this model. Check both room availability and cost records; the example neither predicts demand at a different price nor recommends a room rate.


