Business Gain Lookback
Trace prior losses by year.
Estimated reading time: 1 minute
A prior section 1231 loss can change a later business gain’s character without being deducted again.
Consider a fictional calendar-year U.S. individual with correctly computed net section 1231 results: an $8,000 loss in 2019, a $6,000 loss in 2021, and a $3,000 gain in 2024. All other earlier years have zero results. The losses were ordinary deductions; no special adjustments apply.
Publication 544 applies remaining losses from the preceding five years, oldest first. The 2024 gain therefore uses $3,000 of 2019’s loss, leaving $5,000 from 2019 and all $6,000 from 2021.
For 2025, the verified net section 1231 gain is $10,000 after all current-year netting and separate depreciation recapture. Its lookback covers 2020–2024: the remaining 2019 loss is outside that window.
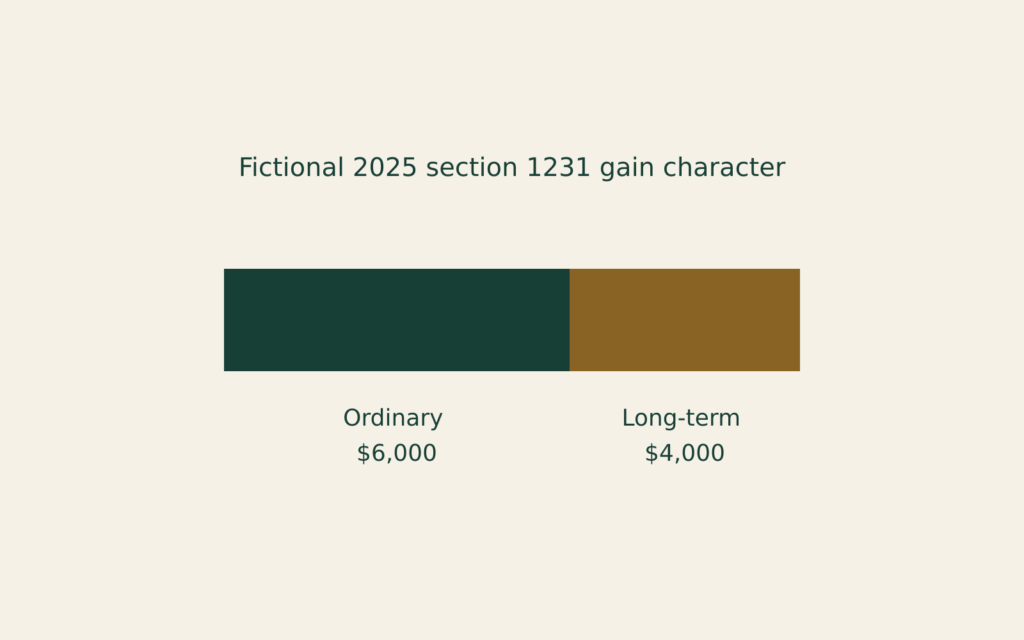
Thus $6,000 of the 2025 gain becomes ordinary income; $10,000−$6,000=$4,000 is long-term capital gain. The 2021 loss is fully used for this lookback.
These are character allocations—not another loss deduction, cash movements or final tax.
Social Security: Retroactive Benefit Tax
Compare two taxable-benefit calculations.
Home Office: Expense Deduction Order
Separate current and carried expenses.
Retirement Formula: From Indexed Total
Follow two rounding stages.