SBA 7(a), 504 or Microloan: Sort the Uses Before Applying
Break a mixed funding request into specific expenses, record unanswered questions and prepare a focused program-use conversation.
Before asking which SBA program fits a business funding request, separate what the money would actually buy or repay. A single total can conceal different purposes. Build a purpose-by-purpose record so your first conversation addresses the unresolved uses, not just the size of the loan.
Give each expense its own line
For each proposed cost, record the amount, recipient, description, date needed and supporting quote or statement. Mark whether it is a new purchase or repayment of existing debt. Where a quote bundles different items, ask for enough detail to distinguish them without changing the actual transaction.
Check for overlap before adding the lines. If a debt balance already financed an invoice in the list, counting both as fresh spending could overstate the request. Keep taxes, delivery or installation visible if they are part of the actual project; ask how they are treated rather than silently labeling everything equipment.
Use three working labels: potentially compatible, excluded for that program, and insufficient information. These are discussion labels, not loan decisions.
Read the program’s uses and application channel together
7(a)
SBA’s 7(a) overview lists working capital, machinery, qualifying real-estate and business-debt uses. Apply through a lender. Broad use categories do not establish that your business or transaction qualifies.
504
SBA’s 504 overview focuses on qualifying major fixed assets, through Certified Development Companies (CDCs). Working capital and inventory are excluded. Some debt consolidation or refinancing can qualify under specified conditions. Equipment must have at least 10 years of remaining useful life; ask the CDC to assess the actual project.
Microloan
SBA’s Microloan overview lists working capital, inventory and equipment among permitted purposes, but excludes paying existing debt or buying real estate. Applications go through an SBA-approved intermediary, which makes credit decisions and sets terms. The program describes loans up to $50,000; that is not an offer to fund your request.
Sort a fictional $51,000 request
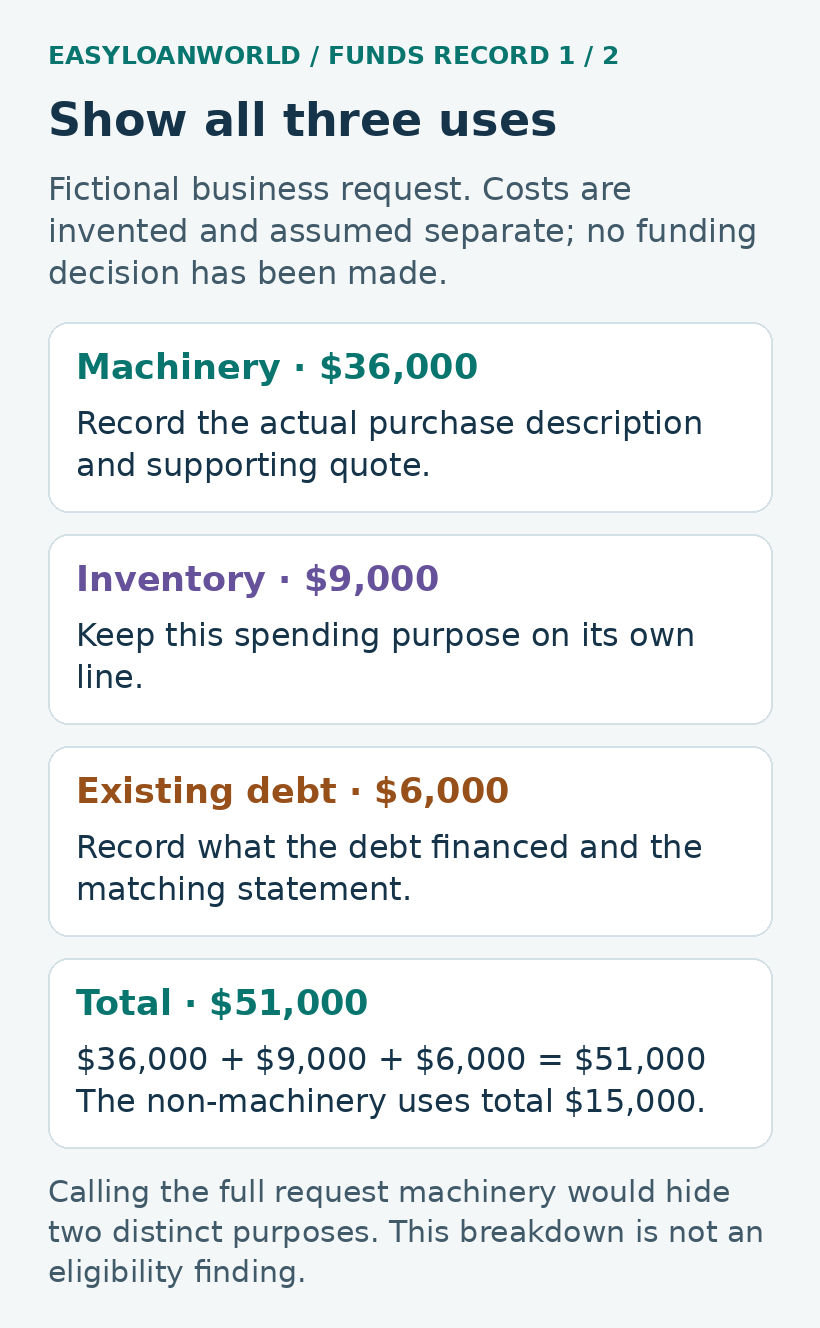
Suppose a business lists $36,000 for machinery, $9,000 for inventory and $6,000 to repay existing business debt. All figures are invented, and the three costs are assumed separate. The owner has not yet obtained a program-specific determination.
The arithmetic is $36,000 + $9,000 + $6,000 = $51,000. Calling the whole request a machinery purchase would lose information about $15,000 of the intended uses.
- 7(a): Ask the lender about this mixed-purpose request; qualification remains unresolved.
- 504: The $9,000 inventory use does not fit. The machinery needs a remaining-life and project review. Whether the $6,000 debt qualifies is unknown, not automatically excluded.
- Microloan: The $6,000 existing-debt payoff does not fit. The machinery and inventory are potentially compatible uses, subject to the intermediary’s review.
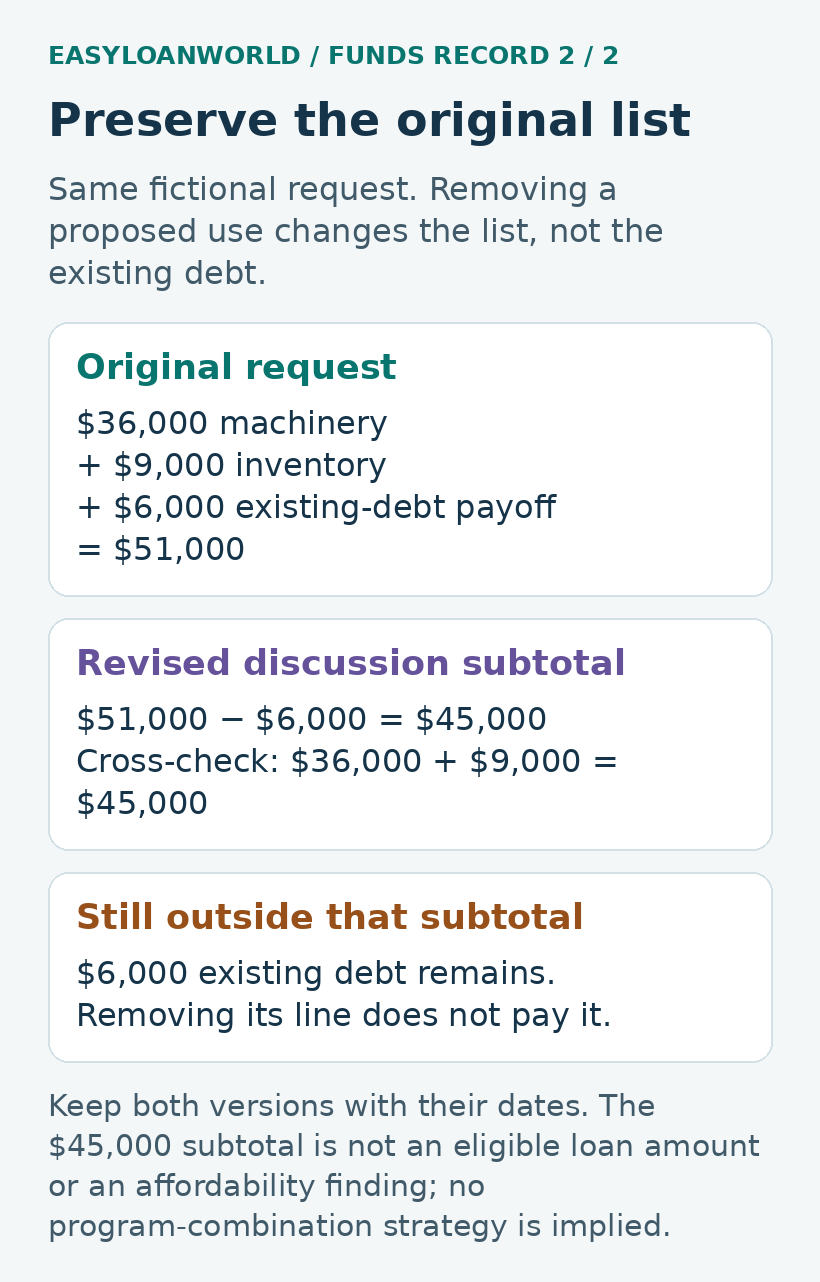
Removing the proposed debt payoff from the discussion gives $51,000 − $6,000 = $45,000, also equal to $36,000 + $9,000. This subtotal is neither an eligible loan amount nor an affordability finding. The $6,000 debt still exists; removing a line from a proposed use-of-funds list does not pay it.
The example identifies questions to resolve. It does not recommend another loan for the excluded amount, combining programs, or splitting an application to bypass a restriction. Keep the original list alongside any revised version so a change in scope stays visible.
Prepare the specific question before sending documents
Choose the relevant official program page above to identify its application channel. Start with a short factual description of the intended spending and the uncertain line. Ask what information the recipient needs to classify that use. Do not send a large document collection before confirming the recipient and request.
For the fictional machinery line, the owner could ask which specifications and ownership or use details are needed for assessment. For the debt line, the owner should identify what the debt financed and ask which records are needed to evaluate that exact transaction. Neither question requires changing the expense’s description to sound more suitable.
Keep a compact contact packet:
- The current expense list, with a version date and a separate total for any proposed revision.
- Matching quotes and debt records relevant to the unresolved purpose.
- The intended timing, including which costs can change and which commitments already exist.
- The recipient’s requested ownership or use facts, recorded accurately.
- A short list of unanswered conditions, with space for the answer and its date.
This packet supports a use-of-funds conversation. It is not a complete application checklist and does not establish approval, an interest rate, payment terms or funding speed.
Record what the answer changes
When you receive an answer, attach it to the specific expense line. Note whether it applies to the described transaction, depends on additional facts, or requires a revised project. A general statement about equipment is not necessarily an answer about your machine, intended use and financing structure.
If a purpose remains unresolved, keep it visible. If you revise the project, update the actual spending plan and total honestly. Compare complete written terms only when an actual financing proposal exists; a potentially compatible use is an earlier checkpoint.
General U.S. business-finance education, not individualized financial or legal advice. Sources checked October 19, 2026. All example costs are fictional; no eligibility or funding outcome is promised.
Featured photo: Hand tools organized in a woodworking space. Photo: Sparsh Paliwal / Unsplash. Used under the Unsplash license.

SBA Surety Bonds vs. Working-Capital Loans: Four Contractor Scenarios
Follow Riverton Build through four fictional alternatives at one pre-start review. Identify what remains unresolved and prepare a focused next conversation.

Export Payment Documents: A Two-Packet Review
A worked export-packet review follows an unresolved instruction proposal, an incomplete selected inventory and an unknown carrier arrangement, without inventing the missing evidence.

Profitable Business, Falling Cash: Reconcile the Difference
An invented one-month example reconciles net income, customer receipts, supplier payments, equipment, debt and an owner distribution to the closing cash balance.