Business DSCR: Check the Inputs and Test Lower Revenue
Follow a fictional earnings bridge, catch an unsupported adjustment and compare the original case with a lower-sales scenario.
Before testing a revenue decline, make sure both versions of your business calculation measure the same thing. A changed adjustment or missing loan can move the answer even when operations have not changed.
Debt-service coverage ratio (DSCR) compares defined earnings with debt payments. Commerce Bank describes EBITDA (earnings before interest, taxes, depreciation and amortization) divided by annual principal and interest, with business, personal and combined analyses. Confirm the actual lender’s adjustments, scope, dates and required level.
Write the definition above the numbers
The following business, agreement and figures are fictional. The invented agreement tests one complete 12-month period. It starts with net income, adds recorded interest, income taxes and depreciation/amortization, then removes a nonrecurring gain. It allows no ordinary payroll addback. Those are assumptions for this exercise, not Commerce Bank’s terms.
The example has no other debts, leases, balloon payments, arrears, fees or personal obligations. A real worksheet should identify unresolved items rather than silently giving them a zero.
Reconcile $100,000 to $150,000
First reconstruct the fictional income statement:
- Revenue: $600,000.
- Variable operating costs: $240,000, or 40% of revenue.
- Fixed cash operating costs: $210,000, including ordinary owner salary.
- Depreciation and amortization: $20,000.
Operating profit is $600,000 − $240,000 − $210,000 − $20,000 = $130,000. Add the $10,000 one-off gain, subtract $18,000 interest and $22,000 income taxes, and net income is $100,000.
The agreement’s adjustment bridge is $100,000 + $18,000 + $22,000 + $20,000 − $10,000 = $150,000. The gain was included in net income, so it is removed once. Starting with gain-excluded net income of $90,000 and then subtracting the gain would remove it twice.
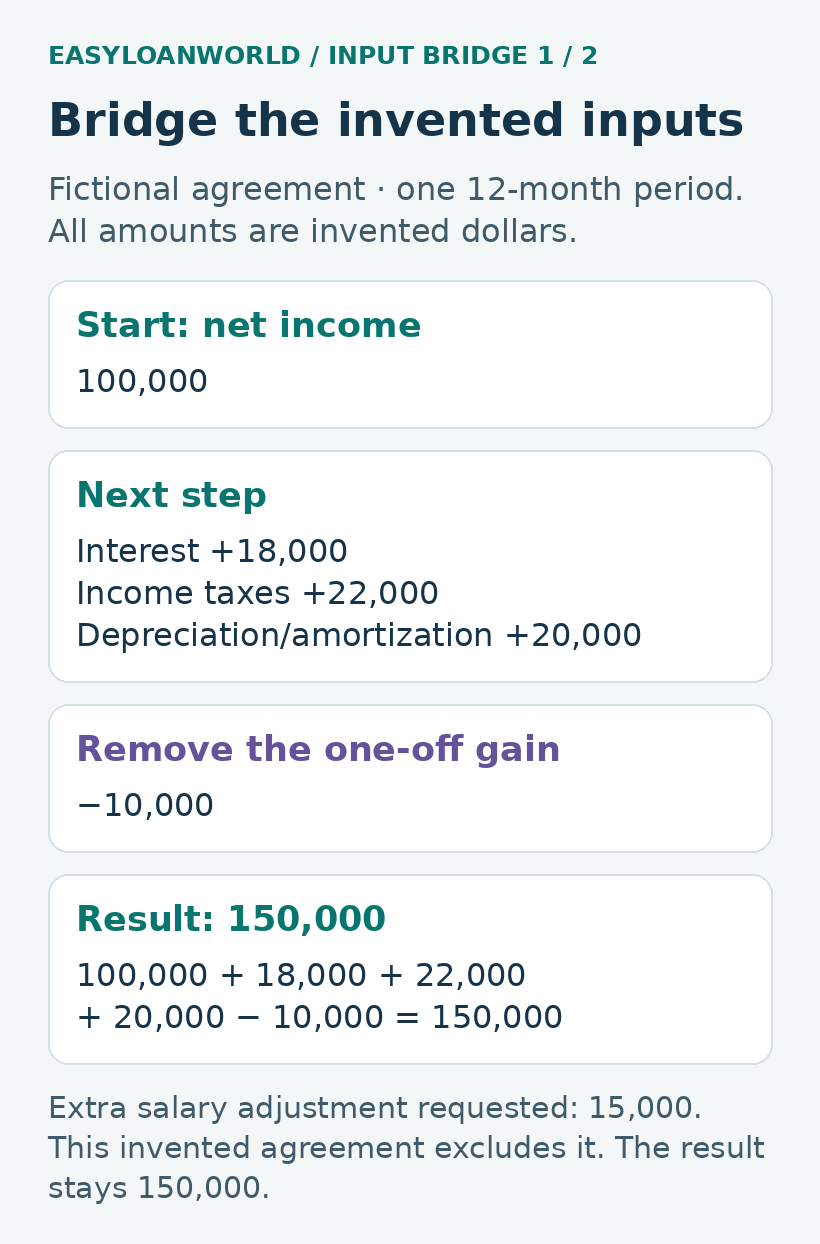
Suppose the owner requests another $15,000 adjustment for ordinary salary. The invented agreement does not permit it. A $165,000 numerator would therefore be inconsistent with this example’s definition. Keep the requested adjustment visible as a rejected line, with the reason, rather than quietly inserting it.
Include the proposed borrowing in its own case
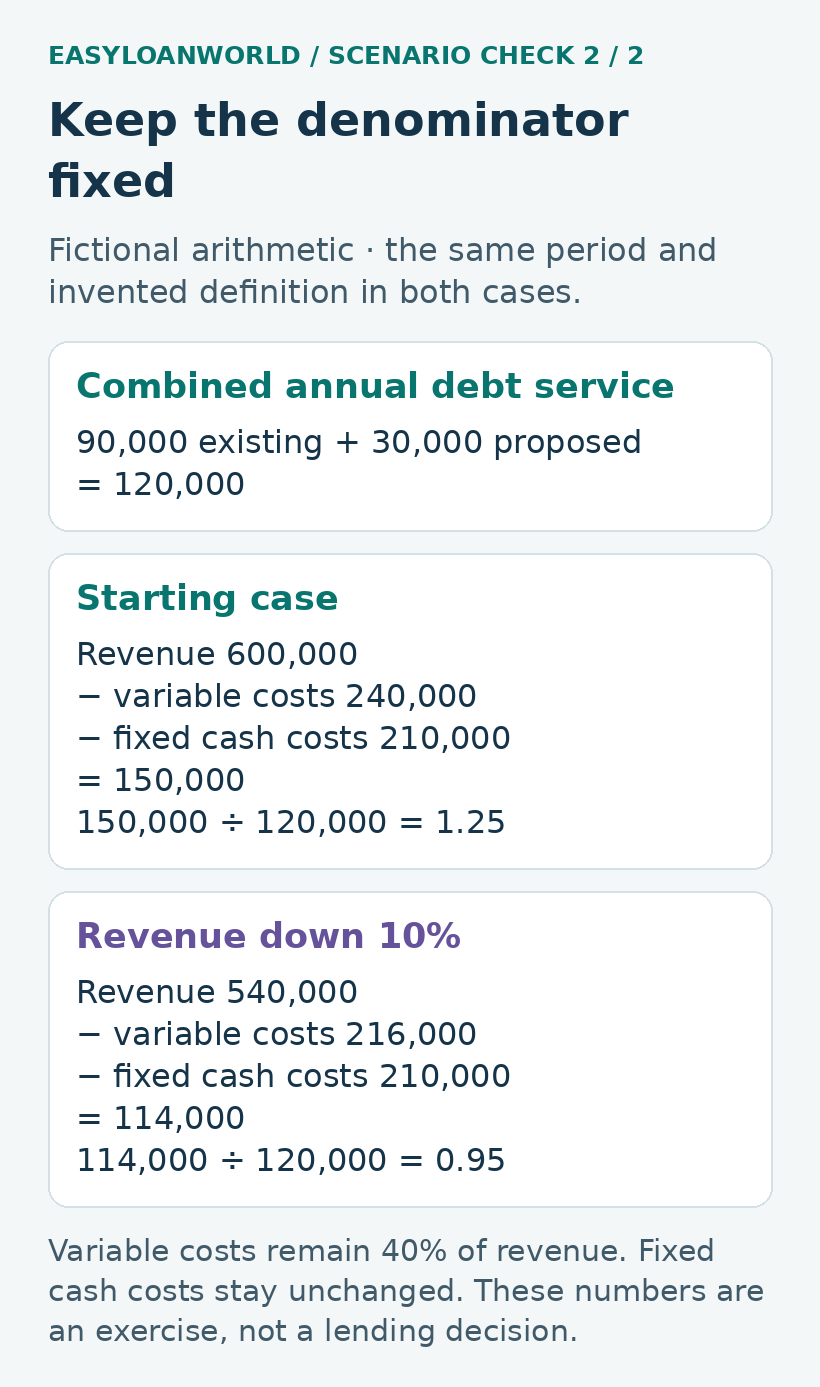
Existing annual principal is $72,000 and interest is $18,000, making $90,000 of debt service. The proposed loan adds $30,000 of annual principal and interest. Combined debt service is $120,000.
- Existing debts only: $150,000 ÷ $90,000 = approximately 1.67.
- Existing plus proposed debt: $150,000 ÷ $120,000 = 1.25.
The first answer does not describe the second borrowing plan. Also notice that the $18,000 interest was added back when building the numerator and included once in debt service. These are different sides of the calculation; deleting it from the denominator would change the defined test.
For a private account-inclusion sheet, give each debt a nickname and record annual principal, annual interest, other required charges, any maturity amount, inclusion status and the lender’s confirmation. Identify the period next to every amount. Keep unconfirmed exclusions separate from the agreed calculation.
Reduce sales without changing the rules
Now reduce fictional revenue by 10%, to $540,000. Variable costs remain 40% of revenue, becoming $216,000. Fixed cash costs remain $210,000. Rebuild the same adjusted numerator directly: $540,000 − $216,000 − $210,000 = $114,000. This is not a new tax forecast.
Debt service stays $120,000, so the downside ratio is $114,000 ÷ $120,000 = 0.95. The numerator is $6,000 below that denominator. A 10% sales decline produced a 24% decline in the numerator because the fixed costs did not shrink.
For an algebra check only, revenue that makes the two sides equal is ($210,000 + $120,000) ÷ 60% = $550,000. That is an 8.33% decline from $600,000. Equality is not a safe borrowing threshold or a lender target.
Record what this calculation leaves unanswered
A ratio alone does not establish loan approval or cash availability. Collection timing, capital spending, taxes, owner distributions and liquidity need separate review.
Keep three dated versions: the agreed starting inputs, the after-borrowing case and the downside. Next to each adjustment, record its original statement line, amount, inclusion status and unresolved question. Ask the lender and accountant to reconcile differences before using the result in a borrowing decision. Keep account details and financial records private.
General U.S. business-finance education. Source checked October 19, 2026. All example figures and agreement terms are invented.
Featured photo: A desk with a calculator and stationery, shown for illustration. Photo: Cht Gsml / Unsplash. Used under the Unsplash license.

SBA Surety Bonds vs. Working-Capital Loans: Four Contractor Scenarios
Follow Riverton Build through four fictional alternatives at one pre-start review. Identify what remains unresolved and prepare a focused next conversation.

Export Payment Documents: A Two-Packet Review
A worked export-packet review follows an unresolved instruction proposal, an incomplete selected inventory and an unknown carrier arrangement, without inventing the missing evidence.

Profitable Business, Falling Cash: Reconcile the Difference
An invented one-month example reconciles net income, customer receipts, supplier payments, equipment, debt and an owner distribution to the closing cash balance.