Mortgage Quote vs. Freddie Mac’s Average: Five Checks
Work through an invented mortgage quote with five record checks. Track what is known, what is missing and what to ask for in writing.
A headline average can prompt a useful question: what, exactly, am I comparing? Before looking for an explanation of a price difference, assemble the records. This five-check exercise ends with a focused request for missing information. It does not calculate a personalized rate.
Start with a deliberately incomplete quote
Fictional example: Alex, the quote and every quote amount below are invented teaching inputs, not an actual offer or a current market estimate. No actual benchmark rate is used.
Alex is considering a conventional purchase loan for a one-unit primary home. The quote says 30-year fixed, with an interest rate of 6.875%. The invented purchase price is $400,000, the loan amount is $360,000 and the down payment is $40,000. That down payment is 10% of the purchase price: $40,000 ÷ $400,000.
Those entries describe this example only. Keep the unanswered fields below open instead of supplying assumptions that make the comparison look complete.
Keep the reference together
PMMS uses selected purchase applications submitted through Freddie Mac’s Loan Product Advisor, rather than completed-loan rates.
The linked November 2022 methodology describes conventional, conforming, fully amortizing, owner-occupied, one-unit purchase loans, with 15- or 30-year fixed terms and a restricted credit/down-payment profile. Applications are not necessarily locked offers or eventual originations.
This guide hasn’t revalidated current numerical criteria.
Ordinary releases arrive Thursday at noon Eastern and summarize the preceding Thursday–Wednesday. Use the calendar for holiday exceptions.
Reference card for this exercise
- Series
- 30-year fixed
- Publication date
- Observation dates
- to
Run the five checks
Read each card as a record check, not a pass/fail score. Its reference points back to the explanation above; its action identifies what Alex should obtain next.
-
Dates
- Reference
- The reference card above.
- Quote
- Received 2026-10-16 at 2 p.m. Eastern. Actual pricing timestamp: unknown.
- Status
- Pricing time unverified. Receipt is later than the displayed reference period; that does not establish when the quote was priced.
- Action
- Ask for the actual pricing timestamp. Save receipt and pricing times as separate entries.
-
Term and product
- Reference
- The series label and dated methodology above.
- Quote
- Conventional, 30-year fixed. Repayment design: unknown. Conforming status: unknown.
- Status
- Limited overlap. The visible term matches; the remaining assumptions have not been established.
- Action
- Request the missing product details. Do not mark the entire comparison complete from the matching label.
-
Transaction, home and borrower
- Reference
- The scope description above.
- Quote
- Purchase; one-unit primary home; the invented down payment shown earlier. Credit profile used by the lender: unknown.
- Status
- Partial and unresolved. Some entries are available; others are missing.
- Action
- Ask which borrower assumptions were used. Do not infer benchmark membership or a price adjustment from this partial record.
-
Number label
A mortgage interest rate excludes loan fees; APR incorporates the rate and additional borrowing charges.
Use the note (interest) rate field and the APR field separately.
- Quote
- Interest rate: recorded above. APR: unknown.
- Status
- Interest rate identified; APR missing.
- Action
- Request the missing disclosure. Preserve each original label; do not copy the example’s interest rate into the blank APR entry.
-
Pricing package
Average fees and points are not reported. That omission does not establish zero-point pricing.
- Quote
- Points: unknown. Lender credits: unknown. Other charges: unknown. Lock status: unknown.
- Status
- Unresolved.
- Action
- Request these entries in writing. A blank stays unknown until evidence fills it.
Turn the open fields into one request
Alex can ask: “Please confirm the assumptions used for this quote, its actual pricing timestamp, repayment design, conforming status, borrower credit profile, APR, points, lender credits, other charges and lock status. Please identify which dated quote your response explains.”
Keep the answer with the quote. Update only the entries it resolves, and retain any remaining unknowns. A replacement quote should get its own record so that details from different versions do not quietly get combined.
The result is a better-defined question. It does not identify what caused an individual price, establish unfairness, rank lenders or predict an approval. Even a fuller record is not a calculation of an appropriate rate.
For an actual offer-to-offer comparison, use the Loan Estimate comparison worksheet. For a separate deadline question, see the mortgage rate-lock guide.
Educational U.S. example; not an individualized mortgage recommendation.
Housing Data: Choose a Caption
Practice choosing a caption for an annotated graphic, then check your answer.
Invoice vs. Bank Payments: Find a $1,000 Double Count
Follow a fictional refrigerator invoice through six bank payments. A complete register and a two-month checkpoint reveal exactly how an incorrect $14,200 total duplicates…
Home-Sales Headlines: Read the Signing and Closing Calendars
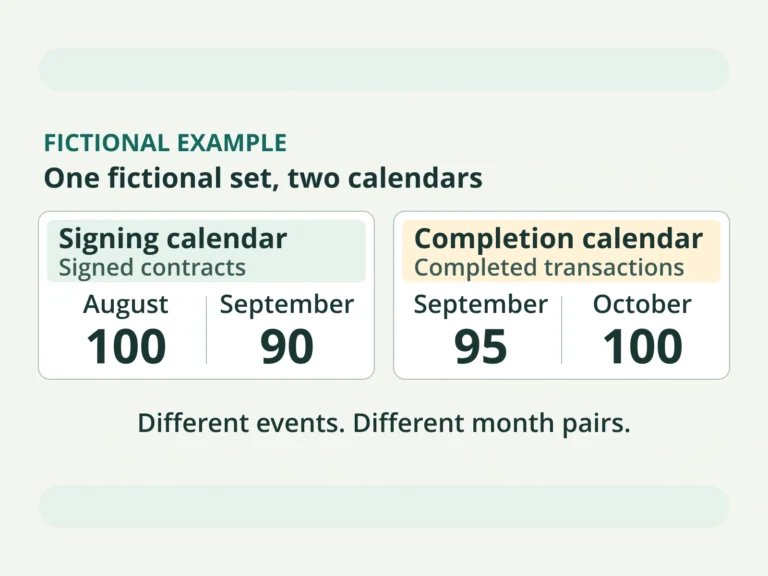
Follow 210 fictional home contracts across signing and closing months, then check which event and comparison base a housing headline actually uses.