New York Financed Insurance Cancellation Refunds
Separate insurer returns from the resulting premium-finance account balance.
Estimated reading time: 1 minute
Assume a New York authorized-insurer property/casualty policy, qualifying premium-finance agreement and valid agency cancellation under §576.
Insurer calculation
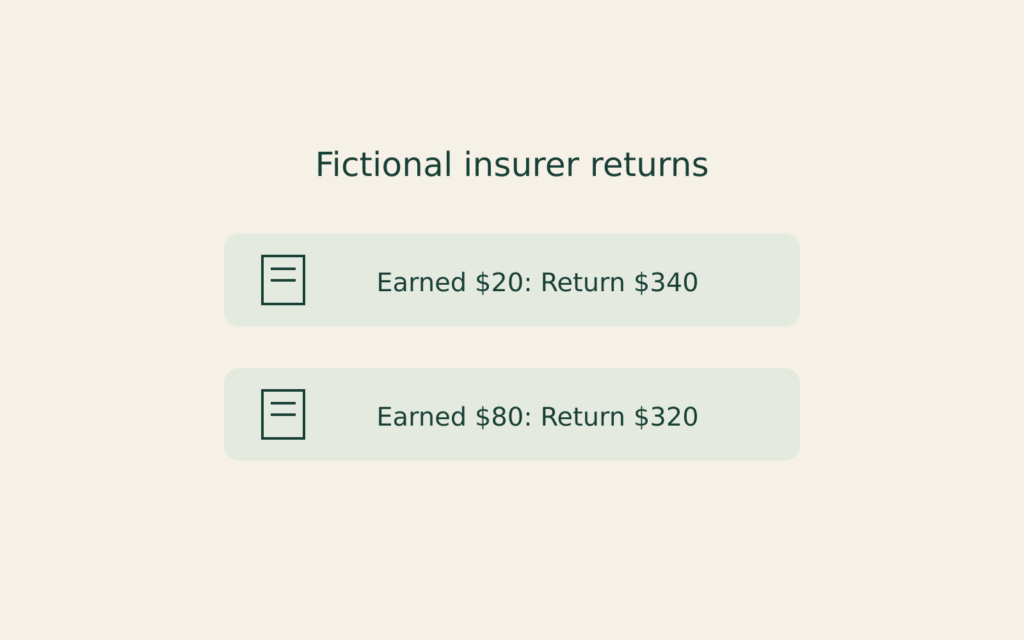
Under §3428(e), assume the insurer exercises its minimum-retention entitlement. Fictionally, it received $400; pro-rata earned premium is confirmed at $20 or $80, with no adjustments, taxes or fees. The minimum is $60, exceeding 10% ($40). Retaining $60 or $80 respectively returns $340 or $320; do not add earned premium and minimum.
Finance account
Assume the agency receives and applies $340, with no other activity. A confirmed pre-credit balance of $250 produces a $90 arithmetic surplus; a separate $400 balance leaves $60 remaining. Neither establishes a borrower payment. These are not legal payoff determinations.
The insurer’s return goes to the agency within a reasonable time, no more than 60 days after effective cancellation—not a guaranteed borrower deposit date. Verify actual posting, coverage status and any payment separately.


