Order and Invoice Evidence
These institutional examples illustrate different records, not universal purchasing rules or permission to pay.
Estimated reading time: 1 minute
These institutional examples illustrate different records, not universal purchasing rules or permission to pay.
Match what arrived
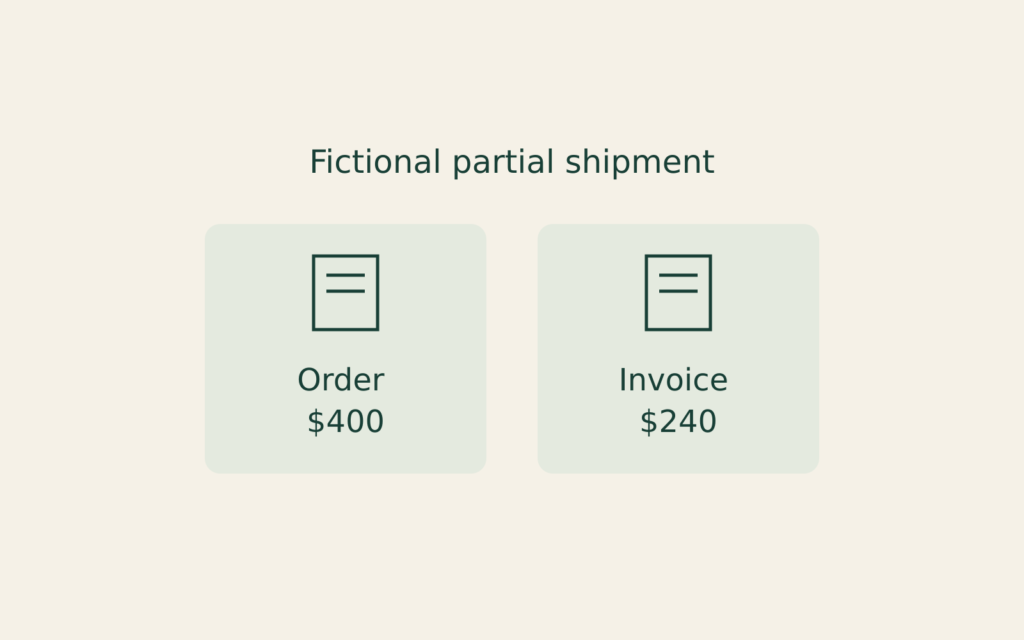
Tennessee’s procedure distinguishes an undamaged partial shipment correctly invoiced from a mismatch. Fictionally, ten units cost $40 each; six arrive and are invoiced. Assume no taxes, freight, deposits or adjustments. The order is $400; the invoice is $240. The remaining four units represent $160 of order value, not another invoice established by these records. This does not determine the remaining contractual obligation.
Identify the document and status
Colorado says its change-order process changes purchase orders, not invoices already entered against them.
Oregon keeps invoices and credit memos separate; a recorded credit can precede collection. Confirm application or refund rather than assuming cash returned.
Ohio State distinguishes invoice-submission acknowledgment from ACH remittance advice; multiple payments may form one deposit.
Smith distinguishes invoices from packing slips, acknowledgments and statements. Verify what the actual buyer accepts.
Form W-9 supplies taxpayer identification to an information-return filer, not delivery evidence. Use verified private instructions for sensitive records.