Flight Training Before Borrowing
Review the flight-training estimate, funding conditions and aircraft-rental exposure separately before borrowing.
Estimated reading time: 5 minutes
A flight-training estimate is only part of the borrowing decision. Review it alongside the funding conditions and aircraft-rental exposure. The independent examples below don’t form a combined offer.
Don’t price a certificate from minimum hours alone
The FAA distinguishes approved Part 141 pilot schools from other training providers. It also recognizes that instructors and companies without that school certification can provide high-quality training.
For a private pilot certificate, its school guide describes a normal forty-hour minimum that can fall to thirty-five at an approved school. It cautions that most people need sixty to seventy-five hours. A regulatory minimum isn’t a personalized completion estimate.
Ask which certificate and training route the estimate covers. This guide doesn’t assess flying proficiency or select a school; an instructor must address the training needed. FAA recommends evaluating training quality, not finances alone.
Read what the fixed tuition leaves outside
ATP Flight School’s fixed tuition excludes examiner and knowledge-test fees, pilot gear, and third-party apps or subscriptions. Selected locations carry a training-center premium.
Its graduated payment schedule follows training progress rather than requiring the entire price upfront. Published payment dates are approximate and progress-based.
Identify the starting-experience tier and location. Obtain the separate expense list before treating fixed tuition as all-inclusive.
Recognize a credit line rather than deferred student debt
AOPA Finance describes its Flexible Aviation Loan as an unsecured line of credit for flight training, not a typical student loan. Its page requires AOPA membership and says the credit can support any flight school, certificate or type rating.
Interest accrues daily on the amount advanced, not the unused approved amount, and is charged monthly. The published terms say there’s no loan deferment.
The published maximum is $20,000. Its application checklist calls for proof of income and valid identification. The page identifies pay stubs, W-2 forms and signed tax returns as income-document examples.
Match the school to the actual education-loan product
Sallie Mae describes its Airline Career Loan for participating professional pilot programs. Not every flight school qualifies.
Its process includes school certification after the credit decision, with disbursement directly to the school. For direct applications, its footnote caps the amount at school-certified attendance cost minus financial aid; partner-site applications can have a lower request maximum.
The page also warns that payments during a grace period depend on the selected in-school repayment option. Its prepayment footnote also specifies an allocation sequence: unpaid fees and costs first, then unpaid interest, followed by current principal, as provided in the promissory note.
For VA support, identify the vocational flight pathway
For the listed GI Bill programs, VA requires an existing private pilot license, an FAA-certified Part 141 school or Part 142 center, and a flight program approved for VA benefits.
At enrollment, the stated medical requirement is a second-class certificate valid for second-class privileges, or first-class for Airline Transport Pilot training. Eligibility belongs with VA and the appropriate aviation professionals, not a household budget calculation.
The page excludes DEA benefits from this vocational route while noting possible college-degree access. It also distinguishes Montgomery reimbursement from Post-9/11 payment to the school, subject to the applicable cap. No benefit amount is estimated.
An awarded scholarship can arrive in stages
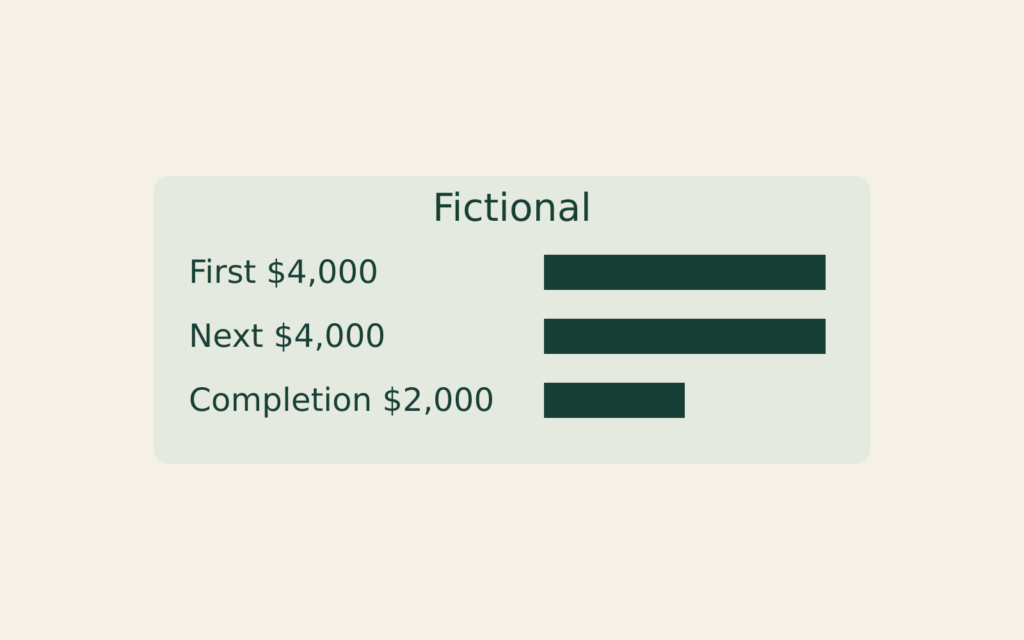
EAA’s flight-training payment description sends money directly to the school: forty percent initially, another forty percent after benchmarks, and twenty percent after completing the certificate or rating.
Fictional illustration: assume a confirmed $10,000 award follows that published split. The installments are $4,000, $4,000 and $2,000. They total $10,000, but the award isn’t a single upfront payment.
Read the actual award documents for benchmarks and the permitted use period. EAA begins disbursement after receiving the winner’s completed documents; an application alone isn’t that documentation. Its application also requires a non-relative character reference to complete a recommendation. EAA says an unfinished recommendation makes the application incomplete at the deadline. Individual scholarships have different selection criteria.
Separate the school’s aircraft policy from your exposure
Avemco explains that a flight school’s or aircraft owner’s insurance protects their interests and may not protect the renter against a lawsuit. Depending on the circumstances, the owner or insurer may seek recovery for damage to the rented aircraft.
Its renter product distinguishes bodily-injury and property-damage liability from optional aircraft-damage liability for negligent damage to the non-owned aircraft. These are different coverage questions, not a single tuition item.
Ask the school about its rental requirements and a licensed insurance professional about the applicable policy. Don’t infer personal coverage merely because the aircraft is insured, or assume a training-loan approval resolves an insurance requirement. This article doesn’t determine liability or choose coverage. Avemco also distinguishes covered legal-defense expenses from the liability limit in its description.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.