New York Coupon Tax Bases
Identify the discount.
Estimated reading time: 1 minute
New York’s coupon bulletin distinguishes manufacturer reimbursement from an unreimbursed store discount.
Same discount, different tax
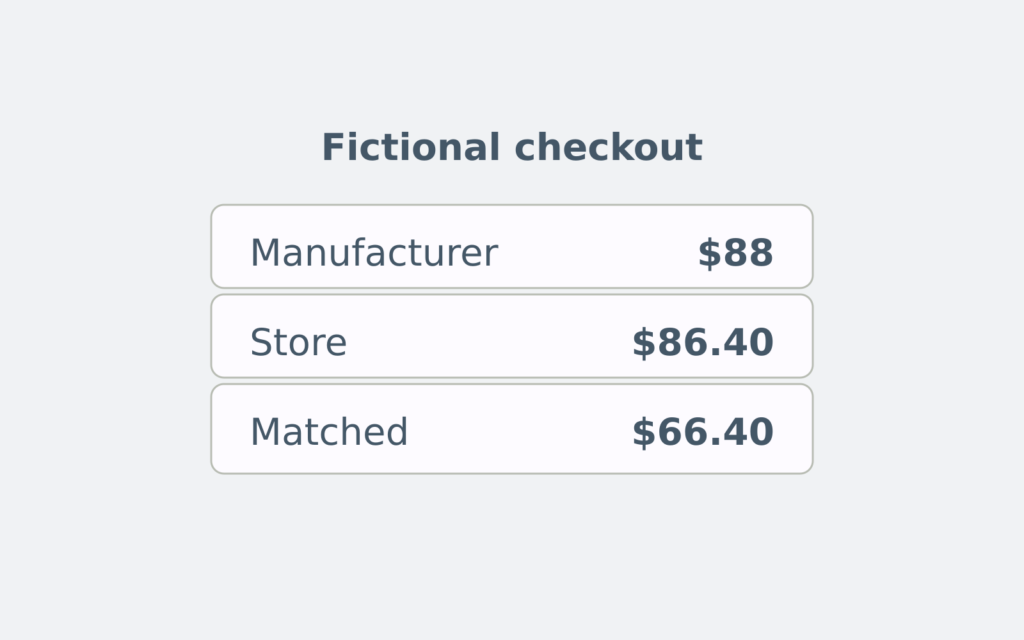
Fictional taxable item costs $100 before coupons. Assume a verified 8% combined local rate, cash payment, no other charges, exemptions or promotions. This is not a statewide rate.
A $20 coupon clearly marked as a manufacturer promotion leaves $100 taxable. Tax is $100 × 8% = $8; customer pays $100 + $8 − $20 = $88.
An unreimbursed $20 store coupon leaves $80 taxable. Tax is $80 × 8% = $6.40; customer pays $86.40.
Store matching changes the base
If the store matches that $20 manufacturer coupon with its own unreimbursed $20 discount, only the store portion reduces the tax base. Tax is $80 × 8% = $6.40; customer pays $100 − $20 − $20 + $6.40 = $66.40.
Check coupon markings, reimbursement and the receipt. Unmarked reimbursed coupons have separate collection rules. This example excludes those, SNAP and prepaid vouchers; do not apply it nationwide.
Roth Conversion and Account Clocks
Separate five-year tests.
ABLE Distributions Across Month-End
Separate retained purposes.