Installment Sale Receipts and Gain
Separate installment-sale principal, basis recovery, gain and interest in a worked land-sale example using the gross-profit percentage and IRS Publication 537.
Estimated reading time: 1 minute
An installment-sale receipt can include interest, recovered basis and gain—not just sale income.
Separate the payment components
Under 2025 IRS Publication 537, the gross-profit percentage applies to payments after removing interest.
Assume a nondealer individual sold investment land to an unrelated buyer in 2024 for $100,000, using the installment method without electing out. Verified adjusted basis was $60,000. There were no selling expenses, debts, depreciation, contingencies or other adjustments. The buyer paid $20,000 down; the ordinary note for the remaining $80,000 has verified adequate stated interest.
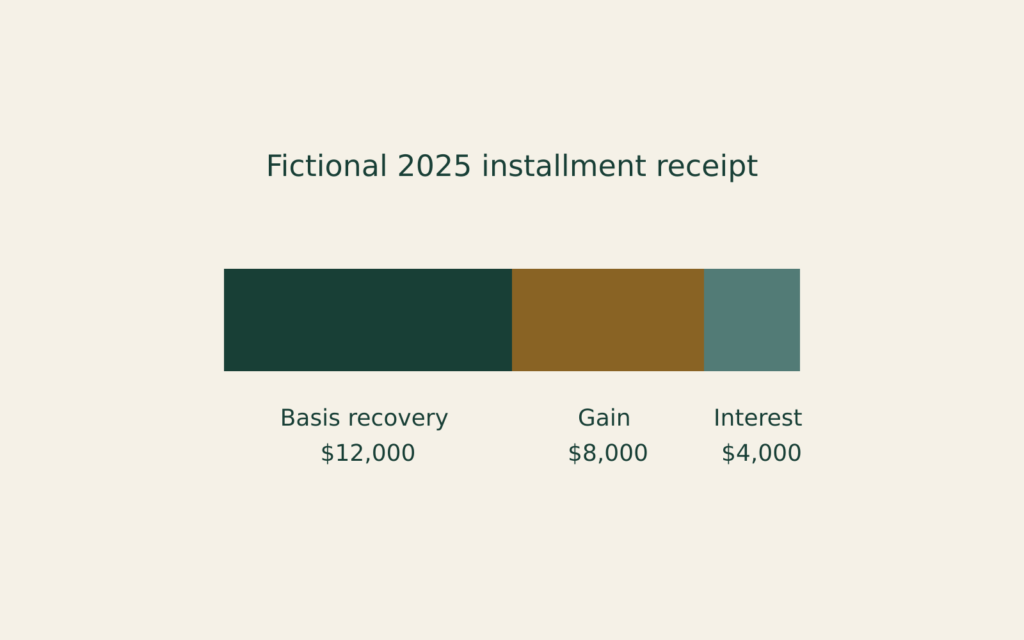
In 2025, the seller receives $20,000 principal plus $4,000 correctly computed interest. No price change, special payment, pledge, disposition or other transaction occurred.
- Gross-profit percentage: ($100,000 − $60,000) ÷ $100,000 = 40%.
- 2025 gain: $20,000 × 40% = $8,000.
- 2025 basis recovery: $12,000.
- Separate ordinary interest income: $4,000.
The $24,000 receipt therefore is not $24,000 gain. The prior down payment is not counted again. This illustration determines neither net taxable gain nor tax owed.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.