Scholarship Restrictions: Tuition and Housing
Check the award restrictions.
Estimated reading time: 1 minute
Unused tuition expenses do not make a housing-restricted scholarship portion tax-free.
Fictional 2025 award
Assume a U.S. resident undergraduate degree candidate attends an eligible U.S. college. An ordinary private scholarship requires $4,000 for tuition and $2,000 for housing, with no teaching, research or other required services. The provider pays all $6,000 directly to the college.
For that semester, required tuition is $5,000 and housing is $2,000. The school applies each award portion as required. There are no other awards, refunds or adjustments.
Terms limit the exclusion
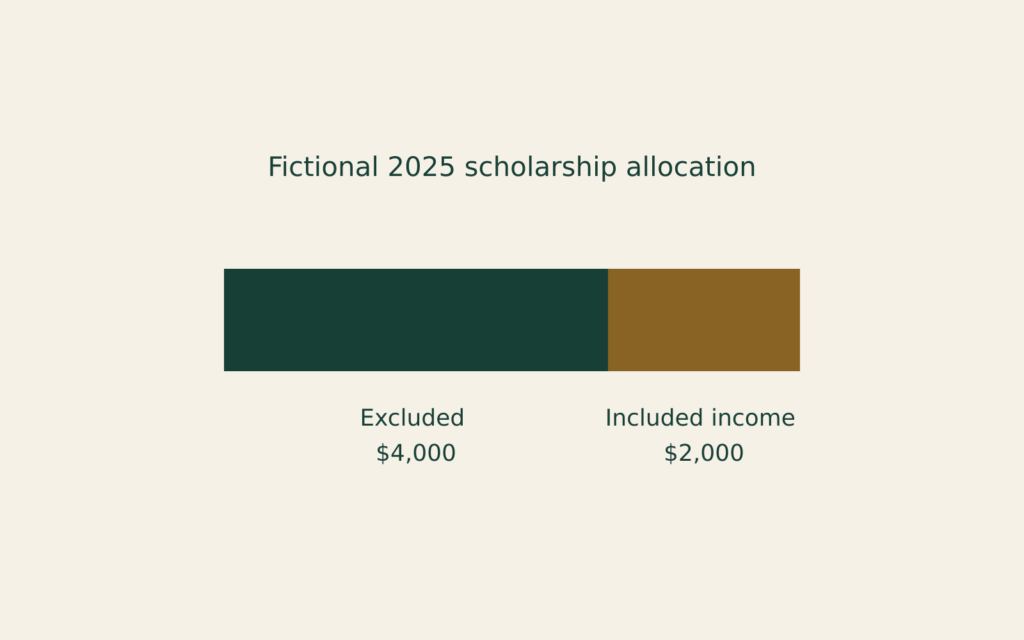
Under IRS scholarship rules, $4,000 is excluded and $2,000 is included in gross income. The remaining $1,000 of tuition does not absorb the housing-earmarked portion: room and board are not qualifying scholarship expenses, and the award’s restriction matters.
Match the award terms with the charges and completed applications. The school received $6,000, but that destination does not establish $6,000 tax-free. The $2,000 inclusion is not tax owed; education-credit coordination and final tax are outside this example.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.