First RMD: Separate Annual Obligations
Receipt totals can cross obligation years.
Estimated reading time: 1 minute
One calendar year’s IRA receipts can satisfy obligations for two different distribution years.
Match payments to the obligation
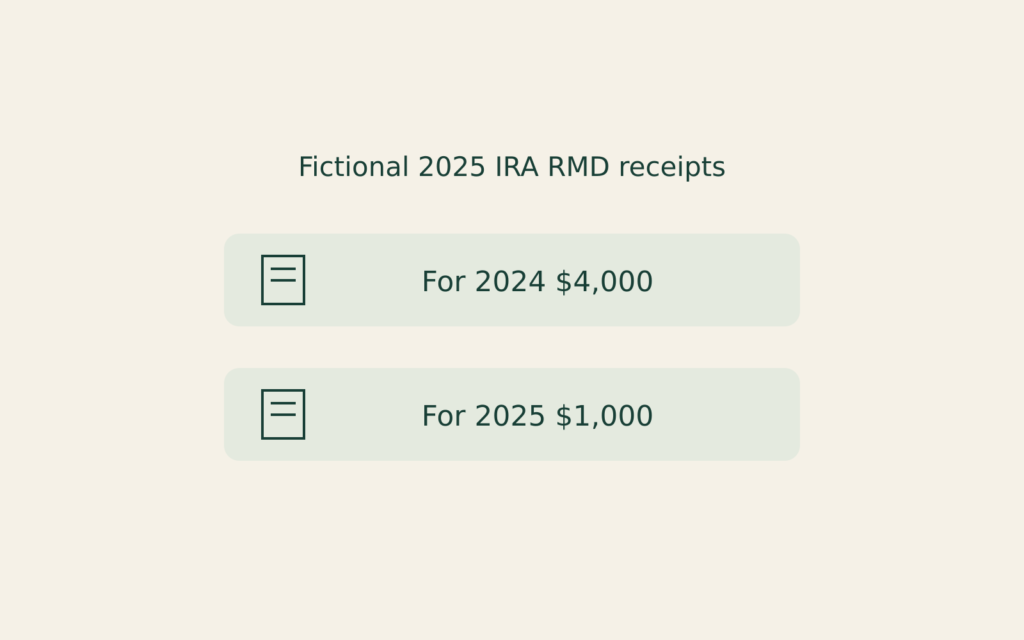
Consider a fictional original owner of one ordinary traditional IRA, turning 73 in 2024 and alive throughout 2025. Correctly calculated required minimum distributions (RMDs) are $4,000 for 2024 and $5,000 for 2025. No distributions occurred in 2024; no special relief or other adjustments apply.
A $4,000 distribution received March 10, 2025, satisfies the first, 2024 requirement before April 1, 2025. A separate $1,000 received July 10 is credited toward 2025. Although calendar-2025 receipts now total $5,000, another $4,000 is needed for the 2025 requirement by December 31, 2025. The March payment is not counted twice.
IRS Publication 590-B (2025) distinguishes the first required beginning date from later annual deadlines. Compare each year’s calculation and credited distributions, not merely the annual receipt total. This uses supplied RMD amounts, recommends no delay and does not calculate taxable income, penalties or actual eligibility for relief.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.