Social Security: Tax-Exempt Interest
Calculate the taxable benefit component.
Estimated reading time: 1 minute
Tax-exempt interest can change taxable Social Security benefits without becoming taxable interest itself.
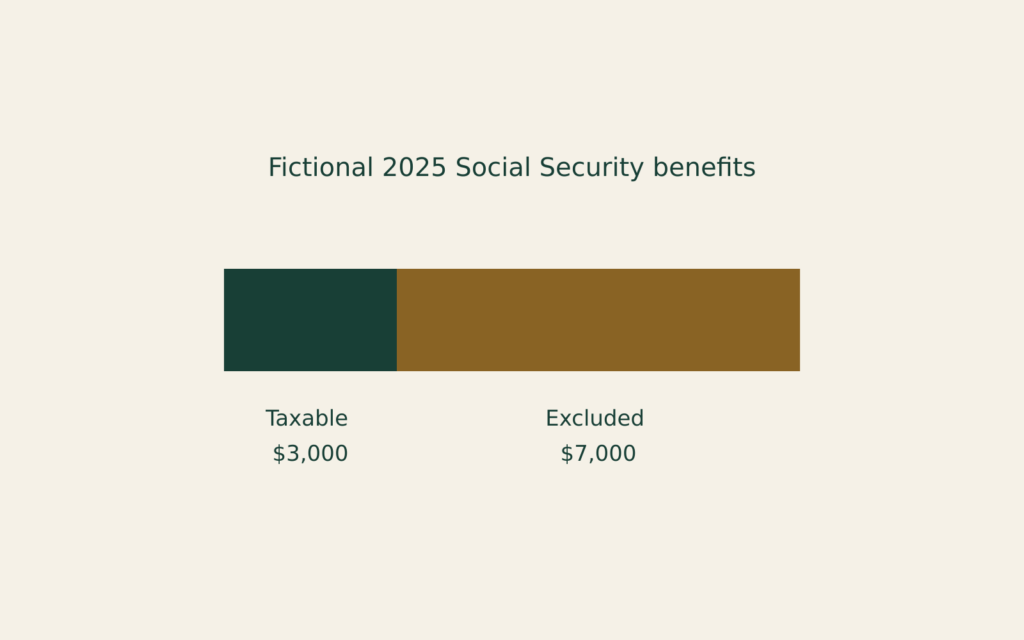
Consider a fictional single U.S. resident citizen in 2025. Verified amounts are $10,000 Social Security retirement benefits for 2025, $20,000 fully taxable pension income and $6,000 tax-exempt municipal-bond interest. There are no other income, adjustments, exclusions, IRA contributions, benefit repayments or prior-year lump-sum benefits.
Apply the benefit worksheet
IRS Publication 915 includes half the benefits: $5,000 + $20,000 + $6,000 = $31,000. Subtract the single-filer $25,000 base: $6,000. This is below the worksheet’s $9,000 interval; half is $3,000, less than half the benefits ($5,000). The higher-band addition is zero. The final comparison with 85% of benefits ($8,500) leaves $3,000 taxable benefits.
Omitting the exempt interest would incorrectly produce zero here. Match pension, interest and benefit records before calculating. The $3,000 is included benefit income—not tax owed, and not taxable municipal interest. This example does not calculate total federal or state tax.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.