Annuity Withdrawals and Remaining Investment
Separate value from unrecovered investment.
Estimated reading time: 1 minute
A partial annuity withdrawal can reduce contract value by more than it reduces unrecovered investment.
One completed withdrawal
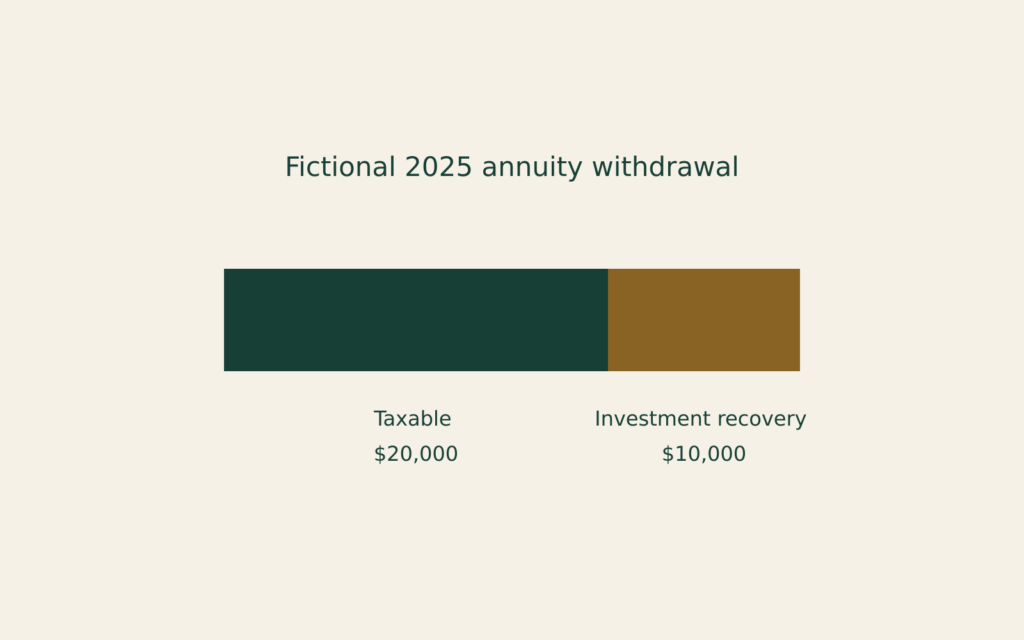
A fictional 65-year-old U.S. owner bought their only nonqualified deferred annuity directly from an insurer in 2020. Before its verified annuity starting date, they take a $30,000 nonperiodic partial distribution in 2025. Immediately beforehand, cash value without surrender charges is $120,000 and verified investment in the contract is $100,000. There are no loans, exchanges, prior distributions, charges or other adjustments.
IRS Publication 575 allocates this distribution first to earnings. The $20,000 excess of value over investment is taxable income; the other $10,000 recovers investment tax-free.
Reconcile what remains
With no intervening value movement, contract value becomes $90,000: $120,000 minus $30,000. Unrecovered investment also becomes $90,000—but by subtracting only the $10,000 tax-free recovery from $100,000, not the full withdrawal.
Keep the distribution and tax-investment records separate. This is not an annuitized-payment calculation, benefit guarantee, withdrawal recommendation or determination of total tax or net cash after withholding.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.