Charitable Bargain Sale Basis
Allocate basis between sold and contributed portions.
Estimated reading time: 1 minute
A charitable bargain sale can produce gain even when its cash proceeds are below the property’s entire adjusted basis.
Separate the sold and contributed portions
Consider a fictional completed 2025 transfer of individually owned investment land to an eligible charity. The owner intends a charitable contribution, and deductibility is independently established. Verified fair market value is $10,000, adjusted basis $4,000 and cash consideration $2,000. No debts, expenses, depreciation or other adjustments apply.
Publication 544 allocates basis between the sold and contributed portions according to their relative fair values when a charitable deduction is allowable.
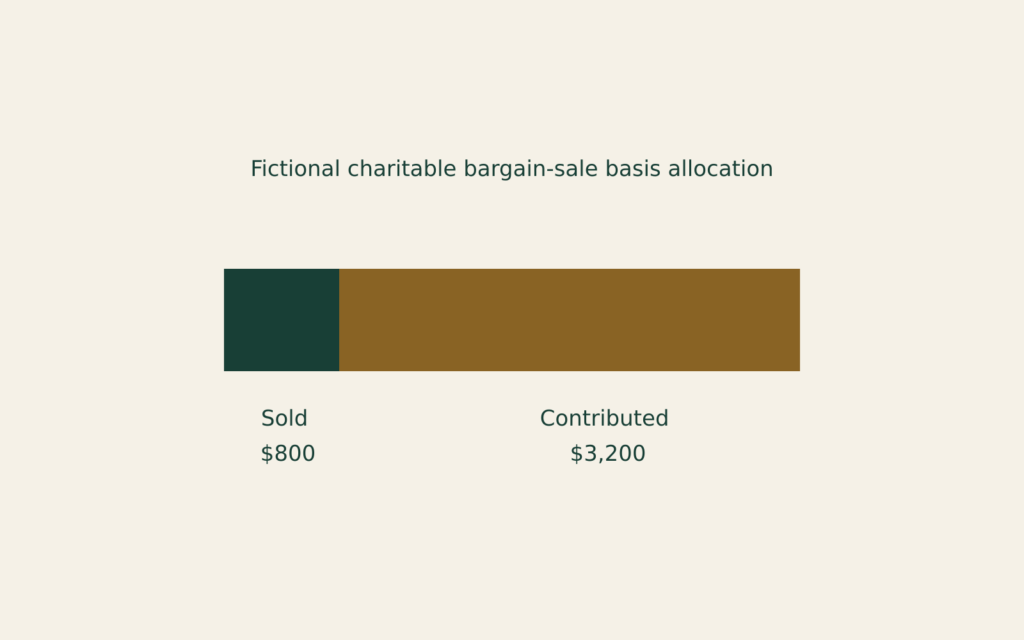
- Sold portion: $2,000 ÷ $10,000 = 20%; allocated basis is $800.
- Sale gain: $2,000 − $800 = $1,200.
- Contributed portion: 80%; allocated basis is $3,200.
The two allocations preserve the $4,000 basis. The $3,200 belongs to the transferred contribution, not property the donor still owns. Subtracting all $4,000 from cash would misstate the sale result. This computes neither the allowable deduction amount nor tax owed.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.