S-Corporation Distributions Before Losses
Reconcile distributions and losses.
Estimated reading time: 1 minute
An S-corporation cash distribution and its allocated loss compete for stock basis in a prescribed order.
In a fictional 2025 case, a corporation has a valid S election and no accumulated earnings and profits. Its sole individual shareholder retains all stock, starting with $10,000 adjusted stock basis. They contribute $5,000 cash capital, receive a $12,000 nondividend cash distribution and are allocated a $6,000 ordinary loss. There are no shareholder loans, prior suspended losses, other income, nondeductible expenses or basis adjustments. At-risk, passive-loss and excess-business-loss restrictions do not further limit the loss.
The IRS ordering rule reduces basis for distributions before losses. The contribution raises basis to $15,000. The $12,000 distribution is within that basis and is nontaxable, leaving $3,000.
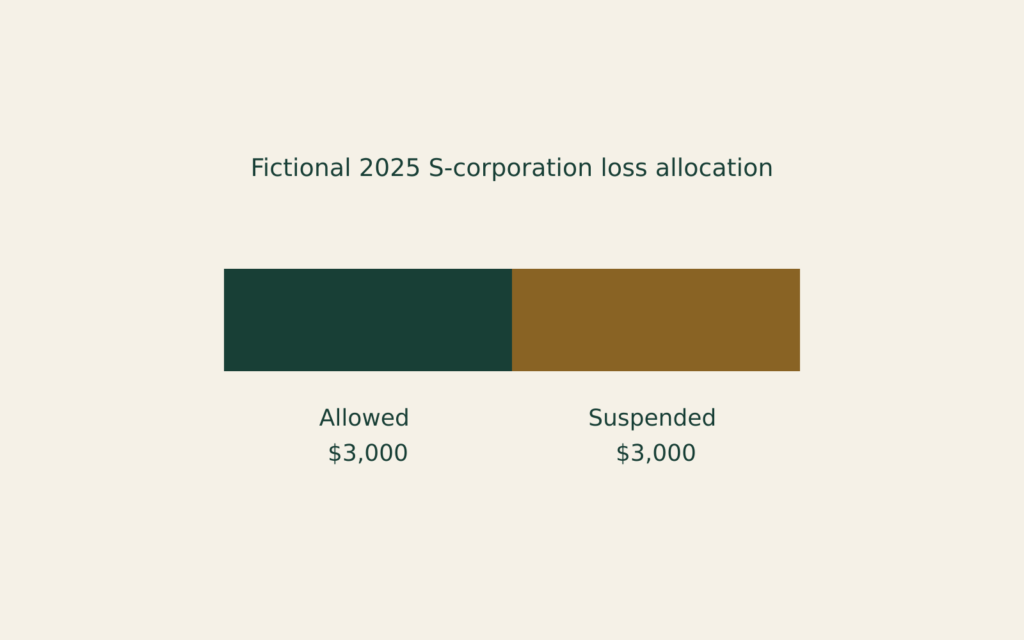
Only $3,000 of the $6,000 loss clears the basis limitation. Closing stock basis is zero; the other $3,000 loss carries forward subject to future basis and other limitations.
Preserve the contribution, distribution and loss records separately. These figures are not tax savings.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.