Partnership Debt and Cash Distributions
Reconcile debt and cash.
Estimated reading time: 1 minute
A partnership can reduce a partner’s tax basis without paying that partner cash.
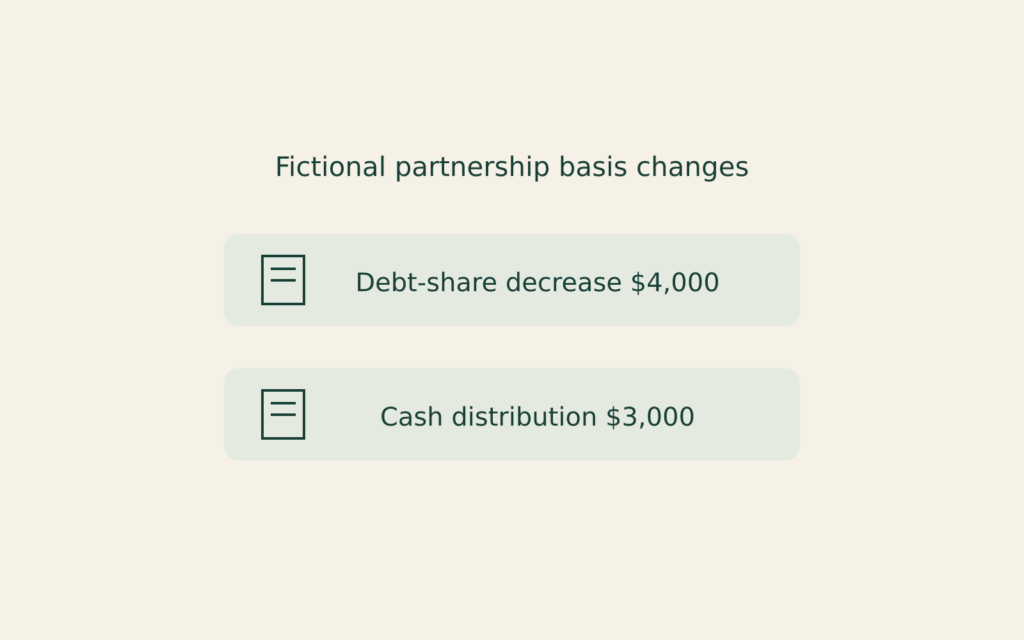
In a fictional 2025 case, a U.S. individual retains an ordinary domestic partnership interest. Its verified adjusted outside basis is $6,000, including a correctly allocated $4,000 share of partnership borrowing. The partnership first repays that borrowing in full, reducing this liability share to zero, then distributes $3,000 cash to the partner. There is no debt cancellation, liquidation, contribution, noncash distribution, unrealized receivables, inventory, special election, or other income, loss or basis adjustment.
IRS Publication 541 treats a decrease in the partner’s liability share as a money distribution. Thus the $4,000 decrease reduces basis from $6,000 to $2,000 before the cash payment.
The subsequent $3,000 distribution exceeds that remaining basis by $1,000, producing capital gain and leaving zero basis. Actual cash received is $3,000, not $7,000.
Reconcile the debt-share change, cash record and outside-basis schedule together. This does not calculate holding-period treatment, net gain or tax owed.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.