Child Credit: Earned-Income Limit
Reconcile refundable credit limits.
Estimated reading time: 1 minute
A refundable child credit can be limited by earned income, not simply the unused child tax credit.
Fictional 2025 case: an unmarried 35-year-old head-of-household filer, paying over half the home’s upkeep, claims their seven-year-old daughter as their only dependent. Both are U.S. citizens living together in Ohio all year. The child provides no support, files no joint return and qualifies for no other claimant. The parent cannot be claimed as a dependent. Both have employment-valid SSNs issued before the return deadline, including extensions; no prior credit disallowance applies.
Verified earned income and modified AGI are each $10,000, entirely ordinary wages. There is no foreign income, combat pay, self-employment or special adjustment. The independently completed income-tax credit limit is zero.
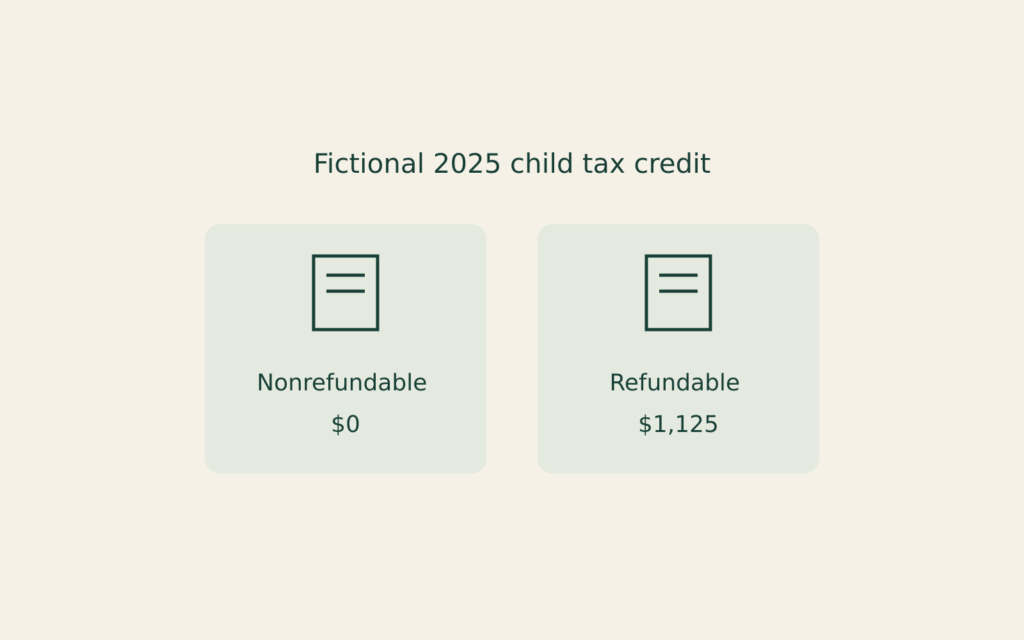
2025 Schedule 8812 produces $2,200 tentative credit, zero nonrefundable credit and a $1,700 refundable ceiling. But ($10,000−$2,500)×15%=$1,125. The additional child tax credit is the smaller amount: $1,125, not $1,700 or $2,200. Other credits and withholding still affect the final refund.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.