Rental Loss Allowance Phaseout
Reconcile current and suspended losses.
Estimated reading time: 1 minute
Active rental management does not necessarily make the entire annual loss deductible.
Reconcile the phased allowance
A fictional single individual directly owns an entire ordinary long-term rental house throughout 2025, meaningfully approves tenants, rental terms and expenditures, and is not a real-estate professional. There is no personal use, disposition, other passive activity, prior suspended loss or credit.
Verified records establish a $20,000 rental loss after basis and at-risk limits; no other deduction limitation applies. Modified adjusted gross income specifically computed for this allowance is $125,000—not an assumed ordinary AGI figure.
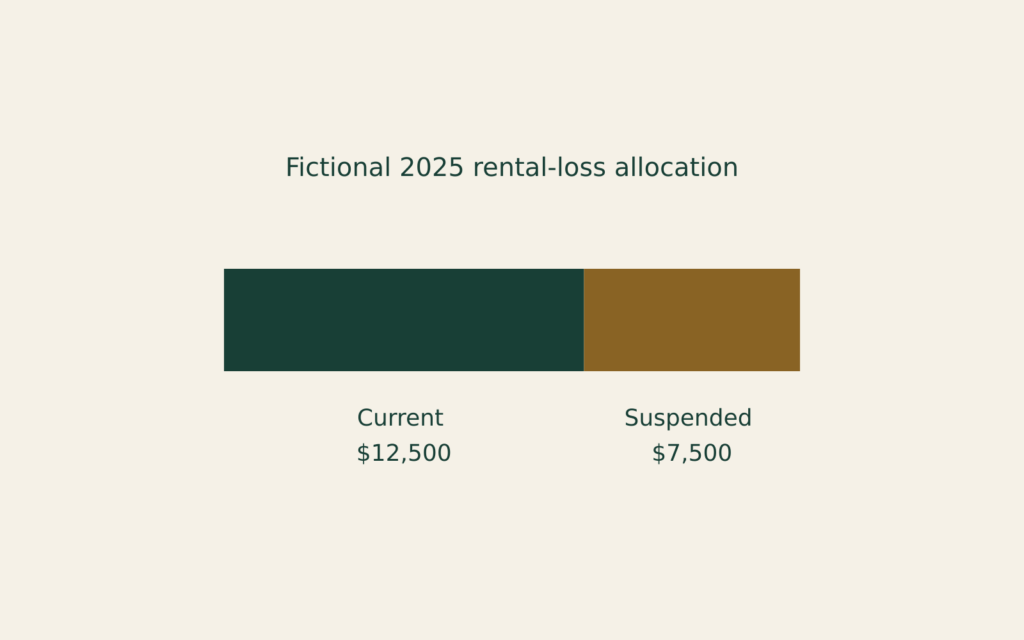
Publication 925 (2025) reduces the $25,000 special allowance by half the amount above $100,000. Here, ($125,000 − $100,000) × 50% = $12,500 reduction, leaving a $12,500 allowance.
Of the $20,000 loss, $12,500 offsets nonpassive income and $7,500 remains suspended. Active participation does not override the income phaseout. Carrying the remainder forward does not guarantee next-year use or determine tax savings.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.