Nonrecourse Funding and At-Risk Losses
Separate funding from loss capacity.
Estimated reading time: 1 minute
Business funding is not necessarily the amount at risk for deducting a loss.
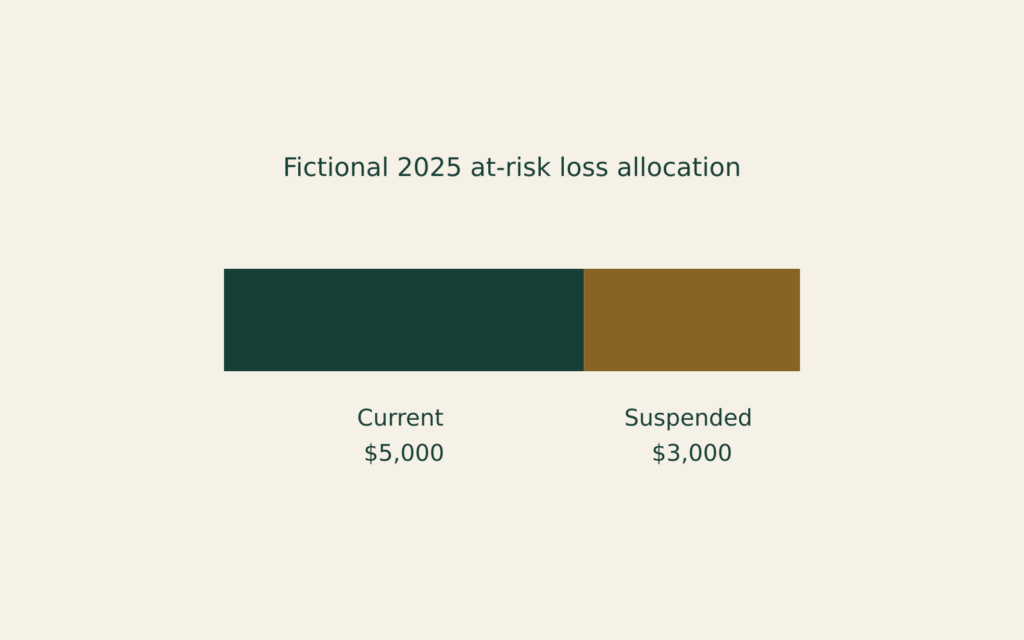
In a fictional 2025 case, an individual starts one sole-proprietor manufacturing business, contributing $5,000 of unborrowed savings and borrowing $15,000 for equipment. The lender can recover only business equipment: the owner has no personal liability, guarantee or outside-property pledge. This is not a real-property activity. No arrangement protects the cash contribution against loss.
There are no withdrawals, other contributions, prior losses or other at-risk adjustments. A verified $8,000 ordinary business loss already satisfies basis requirements. Material participation and other deduction limitations are independently resolved.
IRS Publication 925 excludes this nonrecourse borrowing from the amount at risk. Thus $20,000 total funding does not provide $20,000 of loss capacity: only the $5,000 cash contribution is at risk before this loss.
The current deduction is limited to $5,000; $3,000 remains suspended under the at-risk rules. Future deduction requires sufficient at-risk capacity and satisfaction of other applicable limits, not merely another calendar year.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.