Equipment Use-Change Recapture
Reconcile recapture and basis adjustments.

Estimated reading time: 1 minute
Section 179 recapture can arise while the owner still keeps the equipment.
A fictional calendar-year U.S. sole proprietor bought and placed qualifying nonlisted equipment in service in January 2023 for $10,000. They validly deducted its entire cost under section 179. Its verified ordinary depreciation classification is five-year GDS property, using 200% declining balance and the half-year convention; no bonus depreciation or special adjustments apply.
Documented business use was 100% in 2023 and 2024, then 40% in 2025. Ownership continues; there is no sale, exchange or other disposition.
Publication 946 applies when business use falls to 50% or less during recovery. Table A-1 supplies 20%, 32% and 19.20% for the first three years. Recomputed depreciation is $2,000+$3,200+($10,000×19.20%×40%)=$5,968.
Subtract that from the $10,000 section 179 deduction: $4,032 is recaptured as ordinary income for 2025. The recapture also increases the property’s basis by $4,032.
That basis adjustment is not a new purchase or cash receipt. This does not calculate final tax or subsequent depreciation.
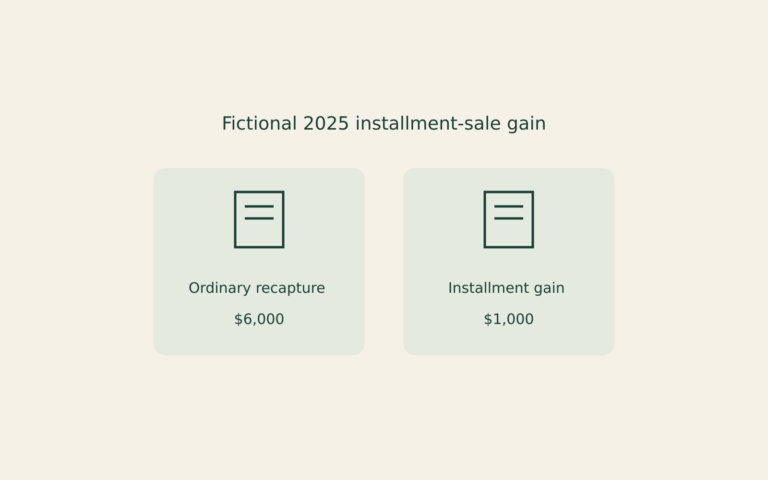
Installment Sale: Recapture First
Reconcile deferred gain.
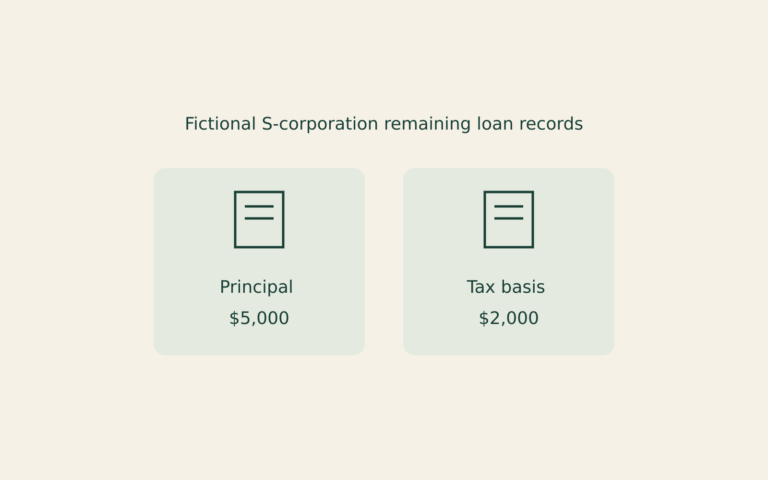
Shareholder Loan: Principal Versus Tax Basis
Reconcile repayment and remaining basis.
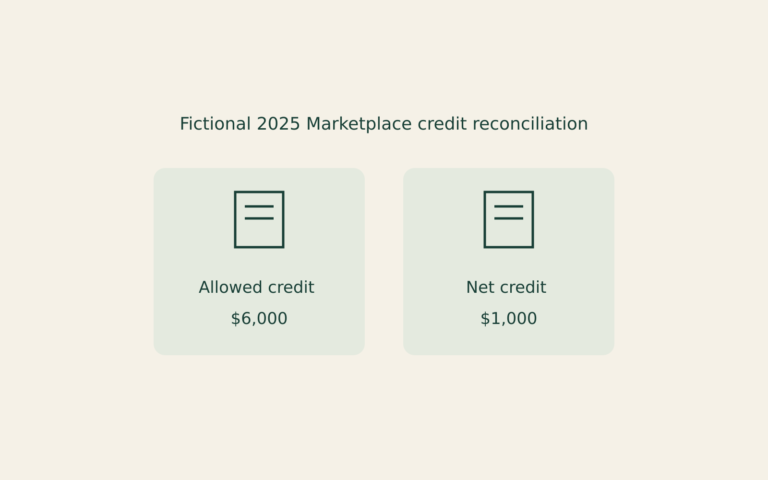
Marketplace Credit: Benchmark and Enrollment Limit
Calculate before subtracting advances.