Shareholder Loan: Principal Versus Tax Basis
Reconcile repayment and remaining basis.
Estimated reading time: 1 minute
Repaying a shareholder loan’s principal is not always entirely tax-free when earlier losses reduced its tax basis.
Fictional case: a U.S. individual directly lends $10,000 cash to their valid S corporation under one bona fide formal written note. In 2024, stock basis is zero and a verified $6,000 ordinary loss is fully deductible after all applicable limitations. It reduces debt basis to $4,000; unpaid principal remains $10,000.
In 2025, the corporation repays $5,000 principal, with interest accounted for separately. There are no other loans, advances, repayments, basis restorations or further basis reductions.
Form 7203 allocates basis proportionately: $4,000÷$10,000=40%. The $5,000 repayment therefore recovers $2,000 basis tax-free and produces $3,000 reportable capital gain because this debt has a formal note.
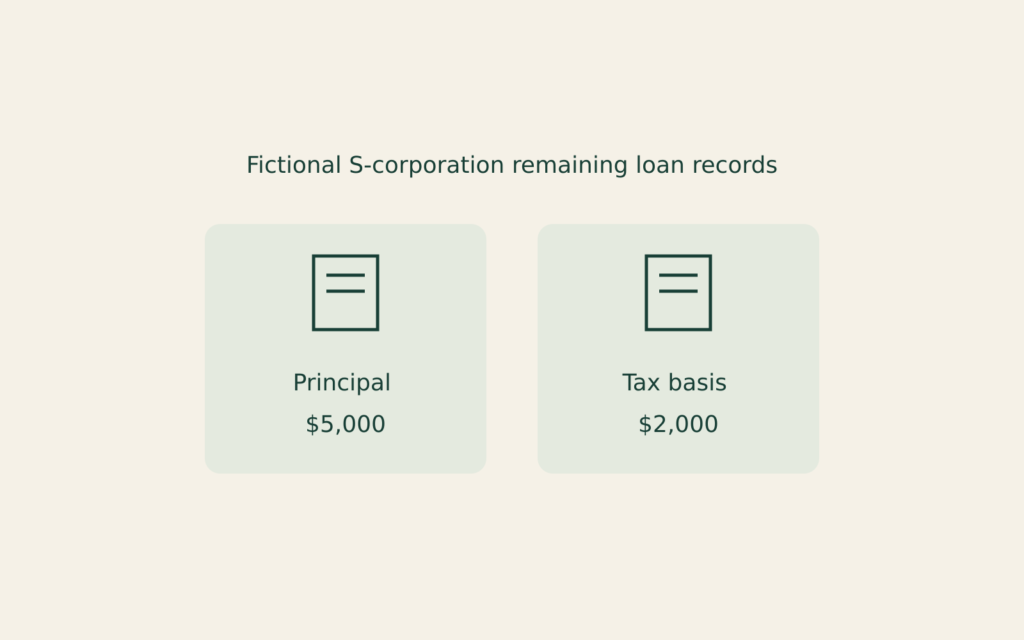
Remaining principal is $5,000, while remaining debt basis is $2,000. Recognizing the gain does not restore basis. The prior loss changed the tax record, not the contractual principal. Holding-period treatment, capital-gain netting and final tax are separate.
Self-Employed Health Insurance Limits
Check coverage eligibility before enrollment.
Wages and Self-Employment Tax Bases
Allocate two different tax bases.
Start-Up Costs and Opening-Year Deductions
Reconcile initial and monthly recovery.