Installment Sale: Assumed Mortgage
Separate selling and contract prices.
Estimated reading time: 1 minute
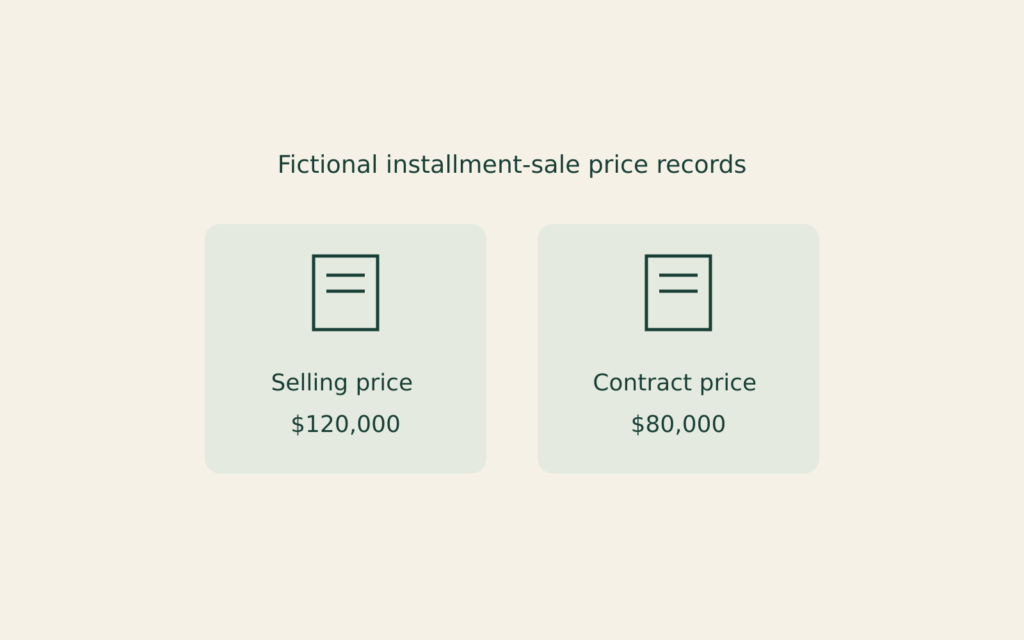
Installment-sale selling price and contract price can differ when a buyer assumes existing debt.
A fictional nondealer individual sells investment land to an unrelated buyer in 2025 for $120,000, using the installment method without electing out. Verified adjusted basis is $80,000. No expenses, depreciation, contingencies or other adjustments apply.
The completed sale includes actual assumption of the property’s $40,000 mortgage, $20,000 cash and an ordinary $60,000 buyer note payable in 2026 with adequate stated interest. No other payments or transactions occur in 2025.
Under Publication 537, this below-basis mortgage is basis recovery, not an installment payment. Contract price is $120,000−$40,000=$80,000; gross profit is $120,000−$80,000=$40,000. Their ratio is 50%.
The $20,000 cash therefore contains $10,000 gain and $10,000 basis recovery. The remaining $60,000 principal contains $30,000 deferred gain and $30,000 unrecovered basis. Basis reconciles: $40,000+
The assumed mortgage is not a second cash receipt. This tax calculation determines neither the seller’s legal release from debt nor final tax; interest remains separate.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.