403(b) Service Catch-Up Limits
Reconcile service and prior deferrals.
Estimated reading time: 1 minute
Twenty years of service does not automatically provide another $3,000 of 403(b) deferral room.
A fictional hospital employee, age 45 throughout 2025, worked full-time for every full annual work period from 2006 through 2025: 20 years. The same hospital was an eligible employer throughout. Its 403(b) plan permits the special 15-year rule.
Through 2024, total elective deferrals with that employer were $98,500, including $14,000 previously permitted under the special rule. All were pretax. Verified 2025 includible compensation is $100,000; no employer contributions, other additions, other plans or special adjustments apply.
Publication 571 increases the regular limit by the smallest of:
- $3,000 annual maximum;
- $15,000−$14,000=$1,000 remaining special-use capacity;
- 20×$5,000−$98,500=$1,500 service-based capacity.
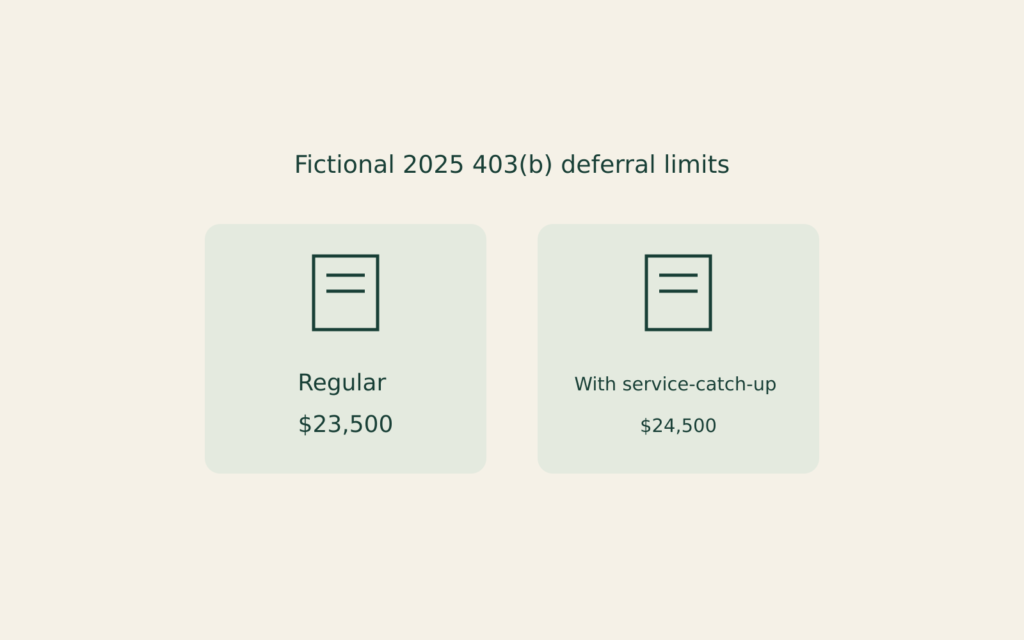
The increase is $1,000, giving a 2025 elective-deferral limit of $23,500+$1,000=$24,500—not $26,500. The prior $14,000 is already within $98,500; it is not subtracted twice in the service calculation.
This reconciles permitted deferral limits, not an actual contribution, employer match, tax saving or recommended payroll election.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.