Property Tax Levy Shares
Compare changing bases.
Estimated reading time: 1 minute
New York’s tax department explains that a jurisdiction divides its levy by total taxable assessments to determine its rate. Your assessment alone cannot explain your bill.
Fictional single-jurisdiction example: a $1 million levy, $50 million taxable assessment base and $200,000 home assessment produce a $4,000 tax: $1 million × ($200,000 ÷ $50 million).
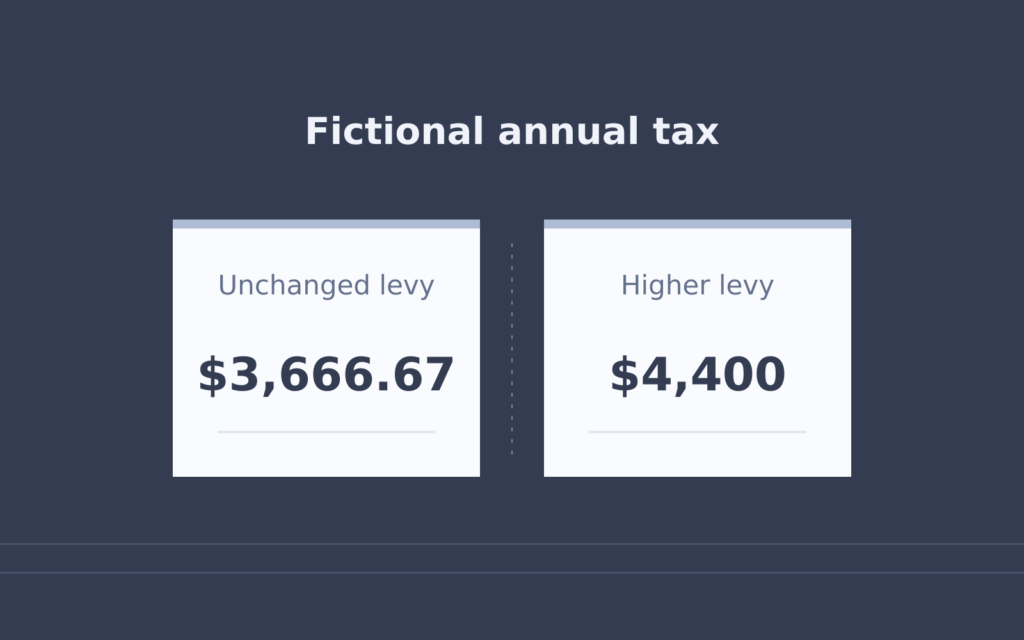
Next year, the base rises to $60 million and the home’s taxable assessment rises to $220,000. With the levy unchanged, the tax becomes $3,666.67. The home’s assessment rose 10%, but its share of the base fell because the base rose 20%.
If the levy instead increases to $1.2 million, the same new assessments produce $4,400. Assessment changes alone did not determine the outcome.
These are alternative annual tax amounts, not amounts to add. Exemptions are already reflected in taxable assessments; other jurisdictions, special charges and cross-municipality equalization are excluded. This simplified model is not a local bill estimate. Before changing a housing budget, verify the actual levy, taxable assessment base and applicable bill components.
Land Release and Mortgage Paydown
Compare proceeds with paydown.