Social Security Spousal Top-Up
Separate benefit components.
Estimated reading time: 1 minute
SSA explains that an eligible person’s own retirement benefit is paid first; a higher spouse’s benefit adds only the difference. Delayed retirement credits on the worker’s record do not increase the maximum spouse’s benefit.
Fictional married couple: assume SSA confirms eligibility, both benefits start without early-claiming reductions, and the receiving spouse files at full retirement age. No other adjustments apply.
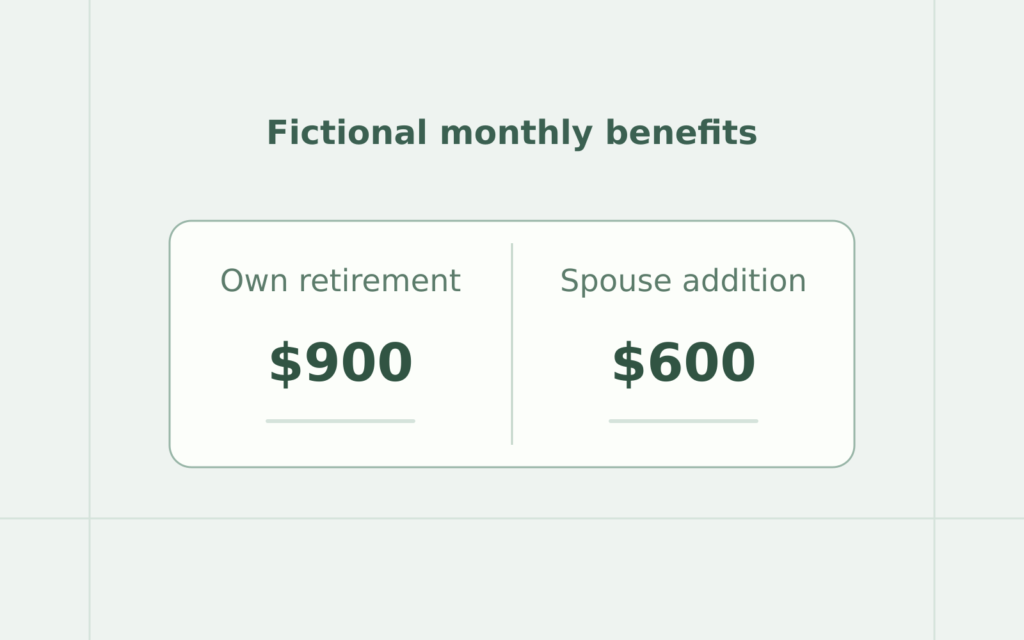
The worker’s full-retirement-age benefit is $3,000 monthly, while their actual benefit with delayed credits is $3,720. The spouse’s own retirement benefit is $900.
The full spouse benchmark is 50% × $3,000 = $1,500—not half of $3,720. The additional spouse component is $1,500 − $900 = $600. Combined benefits for that spouse equal $1,500, not $900 plus another $1,500.
The couple’s combined gross monthly benefits are $3,720 + $1,500 = $5,220. Do not add the $900 again.
This is not a survivor-benefit calculation or a claiming recommendation. Verify actual SSA notices and deductions before treating gross benefits as spendable household cash; earlier claiming or other adjustments can change the result.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.