Fund Fees Counted Once
Identify embedded expenses.
Estimated reading time: 1 minute
The SEC distinguishes fund operating expenses, deducted from fund assets, from separate investment-advisory fees. A reconciliation must identify which charges are already reflected.
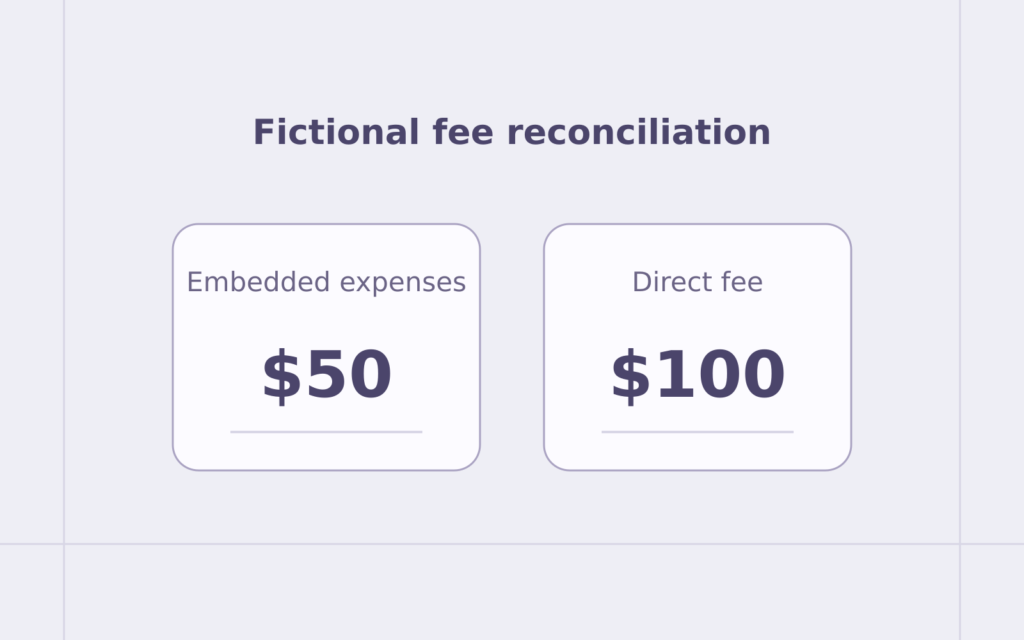
Fictional one-year record: $10,000 invested, no external contributions or withdrawals, and all distributions reinvested. The supplied fund result is $10,600, explicitly after $50 of fund expenses but before an account-level advisory charge.
A separate $100 advisory fee is then debited from the account. Ending value becomes $10,500, leaving a $500 gain relative to the opening investment.
Deducting the $50 fund expense again would incorrectly produce $10,450. That expense is real, but already reduced the supplied result.
Reconcile the costs separately: $50 embedded fund expenses plus $100 direct advisory fees equals $150. The supplied gain before both charges is $650; subtracting $150 leaves the same $500.
These are stipulated dollar amounts, not estimates from an expense ratio. Verify the statement’s period, fee coverage and whether reported performance is gross or net. This example excludes taxes and other charges and does not compare investment suitability or predict returns.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.