Additional Medicare Tax: Joint Wages
Withholding and liability use different thresholds.
Estimated reading time: 1 minute
Correct payroll withholding can coexist with Additional Medicare Tax due on a joint return.
Fictional 2025 wage records
Assume two U.S. spouses file jointly. Each receives $150,000 of verified ordinary Medicare wages from the same private employer. Neither has other wages, tips, self-employment income, railroad compensation or special adjustments.
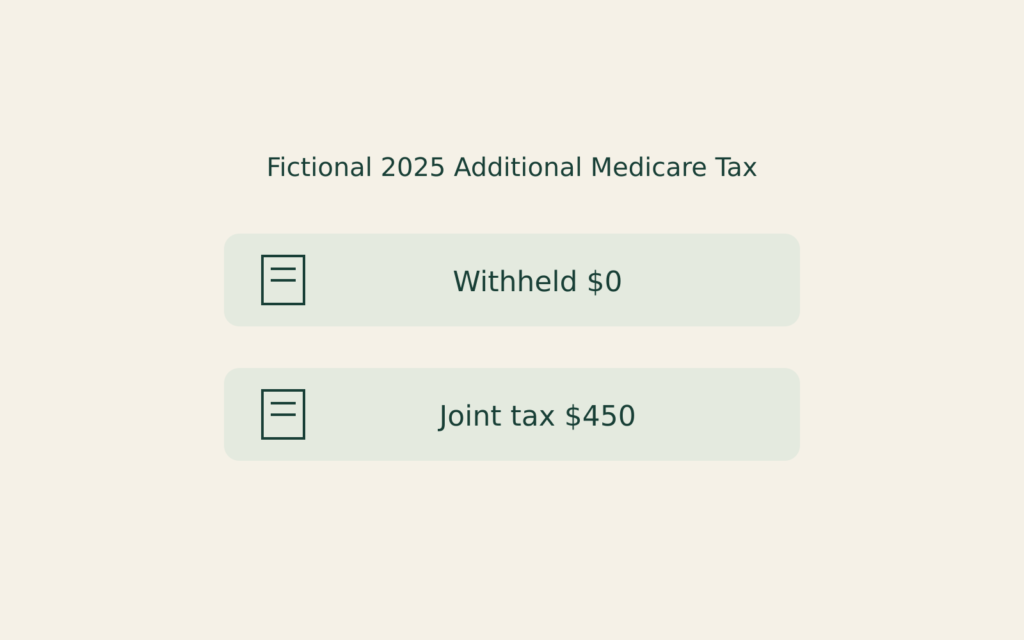
The employer’s withholding test applies separately to each employee’s annual wages exceeding $200,000, regardless of filing status. Neither spouse crosses it; the employer correctly withholds none of this additional tax. Their employer does not combine their wages for that test.
The joint calculation differs
The 2025 joint-return threshold is $250,000. Combined wages are $300,000; the $50,000 excess produces $450 of Additional Medicare Tax at 0.9%.
Match each employee’s wage history first, then the spouses’ combined return calculation. The absence of this payroll withholding is not itself an error. The $450 is this tax component, not the final amount payable after other withholding, payments and credits; ordinary Medicare tax remains separate.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.