Alternative Minimum Tax Reconciliation
Separate tentative and additional tax.
Estimated reading time: 1 minute
Interest excluded from regular income tax can still affect alternative minimum tax (AMT).
Fictional 2025 case: a single, nondependent U.S. citizen, age 40 and not blind, has $100,000 wages and $100,000 interest from directly owned specified private-activity bonds issued in 2015, with no statutory exception. The interest is correctly classified as regular-tax-exempt but AMT-subject, reported in Form 1099-INT box 9; no related expenses apply.
They use the $15,750 standard deduction. No other income, deductions, preferences, adjustments, credits or special tax computations apply. Regular taxable income is $100,000−$15,750=$84,250; the 2025 Tax Table gives $13,455 single-filer tax.
Form 6251 adds back the standard deduction and includes the specified interest: $84,250+
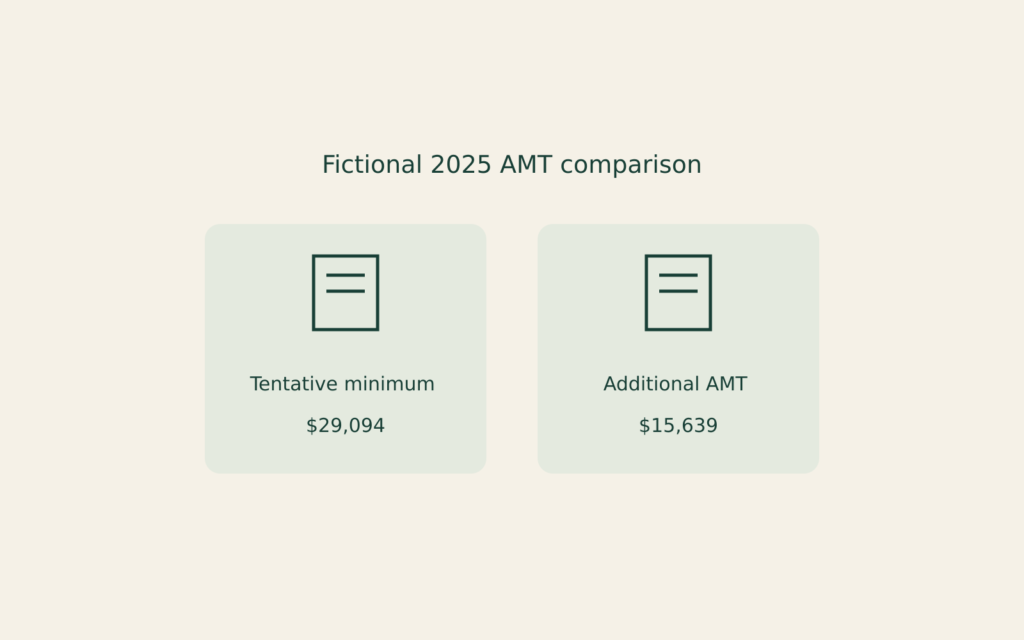
Below the $626,350 phaseout threshold, the exemption is $88,100, leaving $111,900. Below the $239,100 rate breakpoint, 26% produces $29,094 tentative minimum tax.
Subtract regular tax: $29,094−$13,455=$15,639 additional AMT—not another $29,094. Withholding and the final payment balance remain separate.
Mid-Quarter Depreciation Across Purchases
Check the entire acquisition pool.
Self-Employed Health Insurance Limits
Check coverage eligibility before enrollment.
Wages and Self-Employment Tax Bases
Allocate two different tax bases.