American Opportunity Credit: Usable Components
Reconcile tuition and credit components.
Estimated reading time: 1 minute
The American opportunity credit has separate refundable and tax-limited components.
Fictional 2025 reconciliation
A single 25-year-old U.S. citizen cannot be claimed as a dependent. They attend their first year of postsecondary education, enrolled full-time in a degree program at an eligible college for an academic period beginning in 2025, with no felony drug conviction, prior education-credit claims or disallowances. Required identification and Form 1098-T records are verified.
They pay $4,000 tuition during 2025 for that period. There are no refunds, assistance, other education benefits or adjustments. Modified adjusted gross income is $30,000; income tax available to offset is $700, with no other credits.
Publication 970 (2025) gives 100% of the first $2,000 plus 25% of the next $2,000: $2,500.
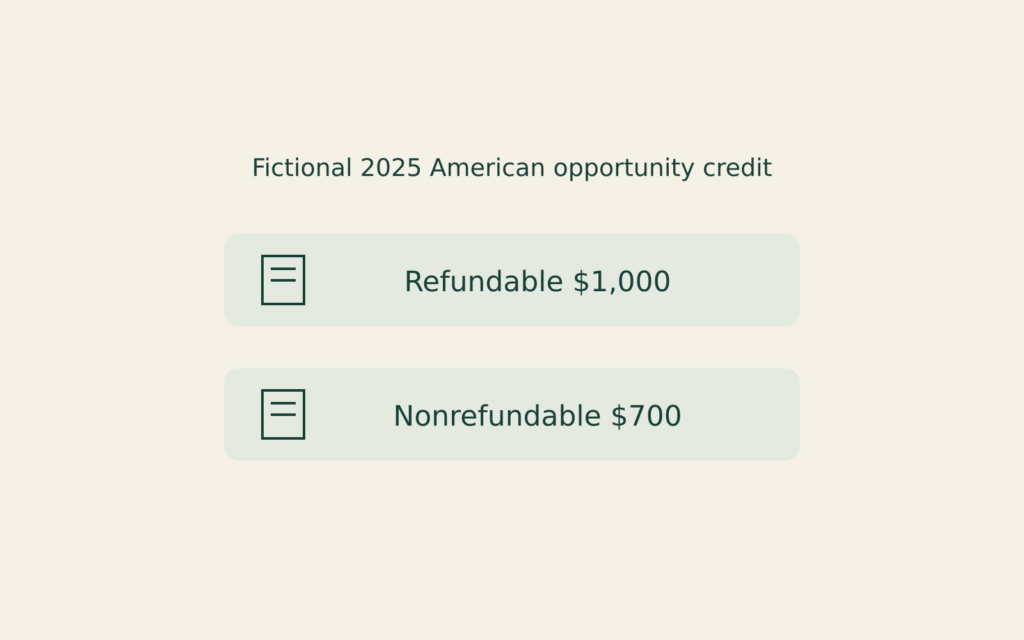
Forty percent, $1,000, is refundable. The other $1,500 is nonrefundable, but only $700 is usable here. The combined credit is $1,700, not $2,500; unused nonrefundable credit does not become refundable.
This computes credit components, not the final refund after withholding and other taxes.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.