Bank Garnishment: Check the Protected Amount
For ordinary-creditor bank garnishment involving covered directly deposited federal benefits, distinguish automatic protection from other exemptions.
Estimated reading time: 1 minute
For ordinary-creditor bank garnishment involving covered directly deposited federal benefits, distinguish automatic protection from other exemptions. Government debts, support orders and IRS levies are outside this example.
Match the bank’s review-time figures
Treasury defines the protected amount as the smaller of covered benefit deposits within the applicable lookback and the account balance when reviewed, including already-posted intraday transactions.
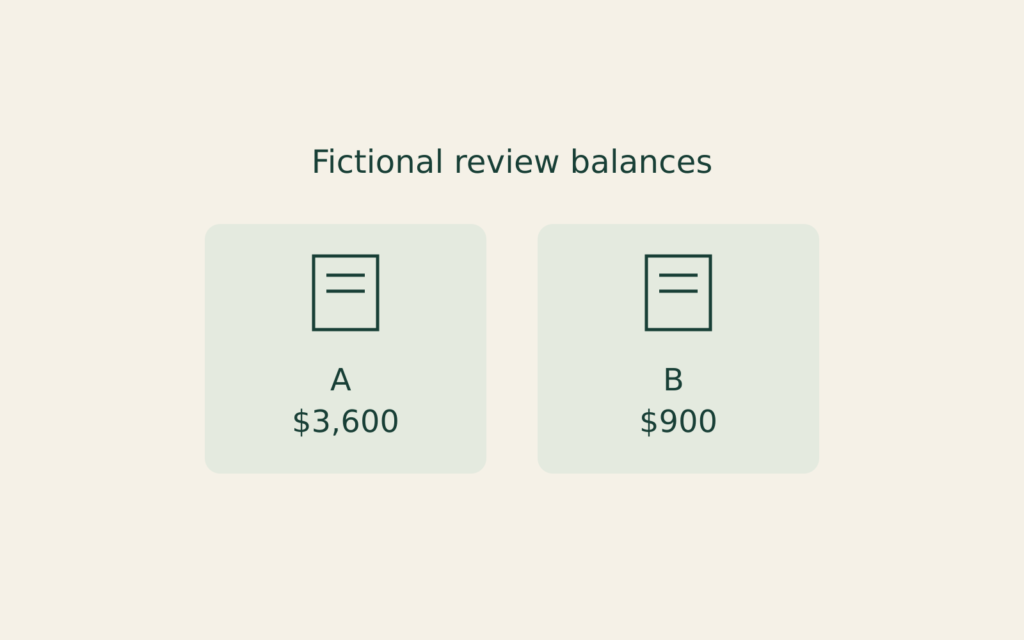
Assume the bank correctly identifies $2,400 of covered deposits within that period:
- With $3,600 at review, $2,400 is automatically protected; $1,200 is outside that amount.
- With $900 at review, the protected amount is $900; the rule does not replenish spent money.
If a $200 purchase posts before review, the first case’s balance becomes $3,400 and the outside amount $1,000.
Outside automatic protection does not establish creditor entitlement. The CFPB explains additional exemptions and legal help. Promptly read the actual notice’s procedures and deadlines; seek qualified help with disputed deposits or exemption claims. This calculation does not decide an individual legal claim.


