Bond Duration Cash Check
Stress the value.
Estimated reading time: 1 minute
FINRA’s duration guide explains that duration estimates a bond investment’s price sensitivity to interest-rate changes. It is not the maturity date.
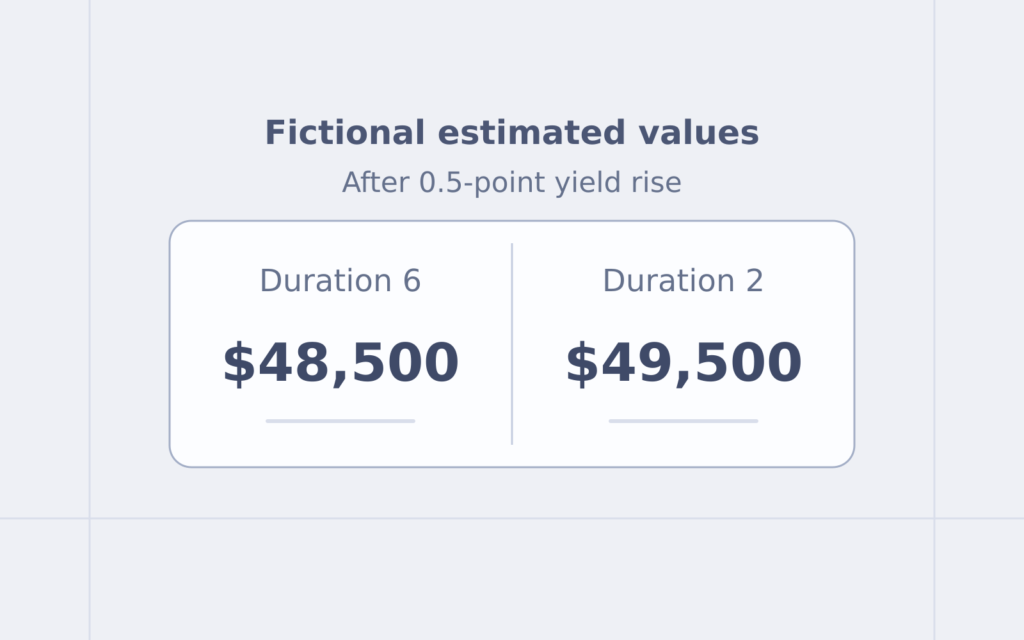
Fictional comparison: two holdings each have a $50,000 market value. Their supplied durations are 6 and 2. Assume the relevant market yield rises from 4% to 4.5%: 0.5 percentage points, not 12.5 percentage points.
Using the duration approximation, the first holding loses about 6 × 0.5% = 3%, or $1,500, leaving $48,500. The second loses about 2 × 0.5% = 1%, or $500, leaving $49,500.
Against a $49,000 payment need, those estimates imply a $500 shortfall versus $500 headroom. Equal starting values did not produce equal cushions.
This isolates a rate shock, not total return. It excludes income, taxes, selling costs and other price changes; actual price responses are not exactly linear.
Confirm current duration, an executable net sale quote and cash availability before funding a bill. Lower duration does not eliminate credit or other risks. Neither estimate guarantees proceeds or recommends a sale.