Business Cash and Tangible Net Worth
Compare equal cash injections, different obligations.
Estimated reading time: 1 minute
The Texas Bankers Association’s covenant guidance emphasizes definitions and adjustments. BDC’s balance-sheet explanation separates liabilities from shareholders’ equity.
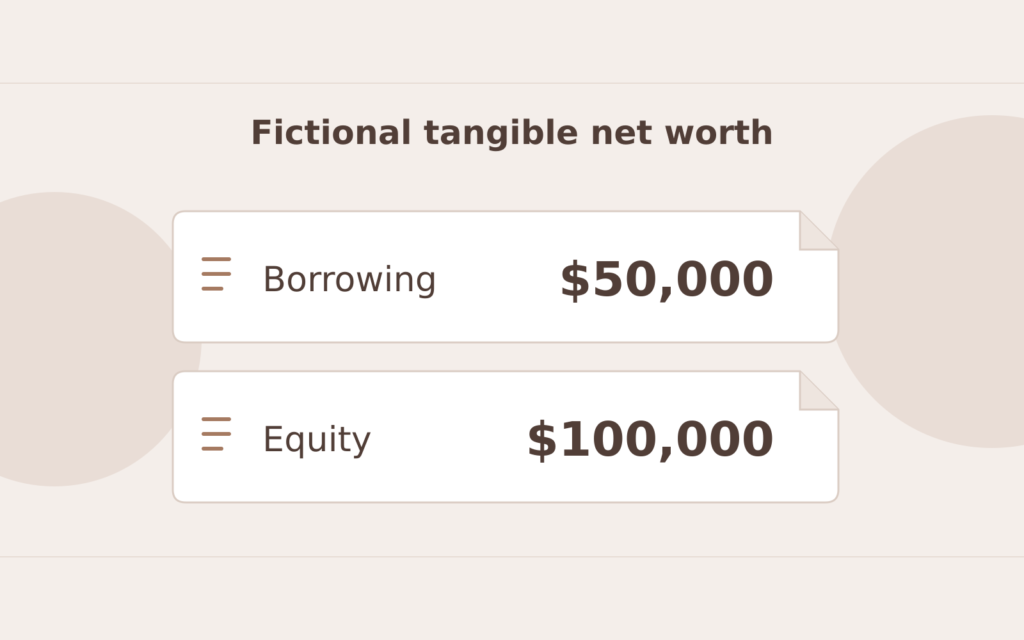
Assume a fictional agreement defines tangible net worth as total assets minus total liabilities minus intangible assets, without other adjustments. Starting assets are $500,000, including $100,000 intangibles; liabilities are $350,000. Tangible net worth is $50,000.
Compare two separately permitted $50,000 cash injections, with no fees, interest accrual or other activity at this checkpoint.
Ordinary borrowing increases assets to $550,000 and liabilities to $400,000. Tangible net worth remains $550,000 − $400,000 − $100,000 = $50,000.
A qualifying equity contribution instead leaves liabilities at $350,000. Tangible net worth becomes $550,000 − $350,000 − $100,000 = $100,000.
Cash rises equally, but the defined net-worth measure does not. Neither calculation establishes repayment capacity. Check your agreement’s treatment of subordinated debt, excluded assets and permitted funding with your lender and accountant before treating a cash receipt as covenant compliance.
Construction Retainage and Cash
Reconcile the current payment.
Marketing Loan Benefit Routes
Compare financing and benefits.
Business and Owner Debt Coverage
Count distributions only once.