Capital Losses: Track the Carryover
Reconcile gain offsets and remaining losses.
Estimated reading time: 1 minute
A capital-loss carryover can offset current gains before the annual deduction limit applies.
Follow one complete year
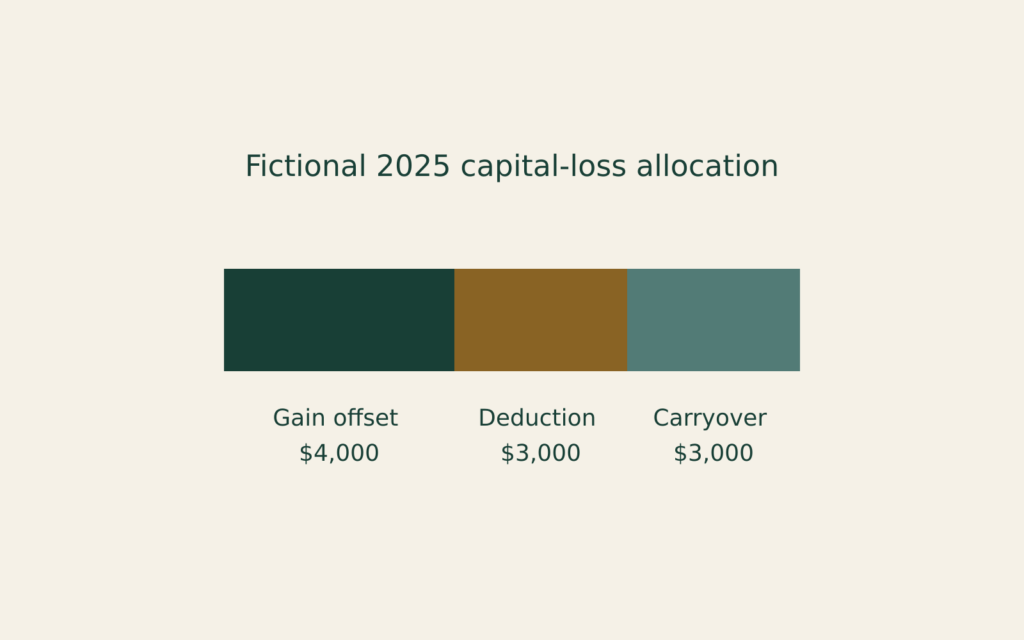
Consider a fictional individual, single throughout 2025 and alive at year-end, with a verified $10,000 short-term capital-loss carryover entering 2025. The only current capital transaction produces a correctly determined $4,000 short-term gain. There are no long-term items, special adjustments or canceled-debt attribute reductions. Taxable income remains positive after the capital-loss deduction.
Netting leaves a $6,000 short-term loss. The 2025 capital-loss deduction is $3,000; the remaining $3,000 carries into 2026 as short-term loss. Thus $7,000 of the opening carryover is used: $4,000 against gain and $3,000 as the deduction—not merely $3,000 overall.
IRS Publication 550 (2025) explains netting, the deduction limit and taxable-income-sensitive carryover calculation. Match the prior carryover record, current gains and taxable income. This is not $7,000 of tax savings, cash received or a recommendation to sell; other circumstances can change the carryover.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.