Checkout Installment Offers
Quick answer: Read the exact loan offered at checkout: creditor, total repayment, fees, payment dates and repayment method.
Estimated reading time: 6 minutes
Quick answer: Read the exact loan offered at checkout: creditor, total repayment, fees, payment dates and repayment method. Then combine its schedule with every installment plan you already have. A manageable-looking payment for one purchase can become a difficult payment day when several plans overlap.
Identify the loan
PayPal’s comparison names PayPal, Inc. as Pay in 4’s lender and WebBank for Pay Monthly. Pay in 4 starts at purchase, followed by three biweekly payments.
Does checking eligibility mean borrowing?
PayPal’s application guidance separates the application from an approved loan actually used. Applying for Pay Monthly doesn’t affect the credit score; an approved, used loan may be reported, including its amount and payment history, and may affect the score.
Its assessment considers application information, credit score, PayPal transaction history and account age, among other factors. An applicant may qualify for one Pay Later product, both or neither. A displayed choice is therefore not a promise of approval. For a declined application, PayPal directs customers to the secure decision message; customer service can’t review the application or see its decline reasons.
PayPal also explains that a new account can still be created when both Pay Later products are declined. Receiving an account doesn’t establish that either loan was granted. Keep the account-opening result separate from each product’s decision message in the secure Message Center.
Do four payments include a financing fee?
Sezzle’s U.S. disclosure gives a Pay in 4 example with a separately stated service fee treated as a finance charge. Actual fees appear at checkout. Its stated service-fee range is $0 to $7.49, depending on purchase price and product; the published illustration doesn’t determine an individual offer’s fee. Don’t infer zero financing cost from the number of installments.
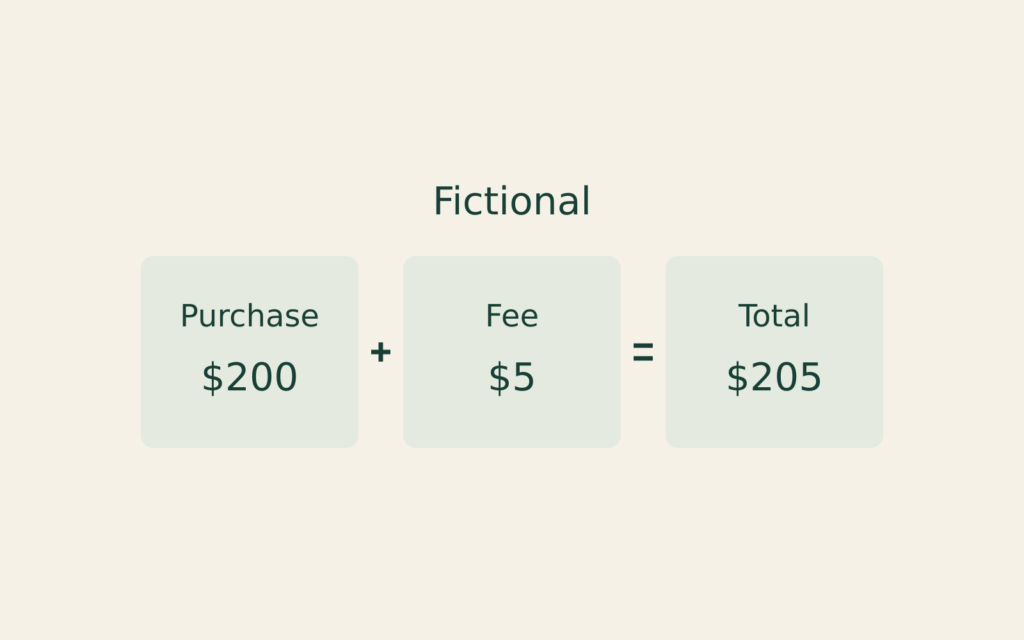
Fictional arithmetic, not a Sezzle offer: assume a $200 purchase plus a separate $5 financing fee, with no other charges.
| Purchase amount | $200 |
|---|---|
| Separate fee | $5 |
| Total paid | $205 |
The $5 isn’t counted twice. It isn’t a quote. If a real schedule already includes its fee, adding it again overstates the total. This exercise doesn’t calculate APR: payment timing and the actual disclosure remain necessary. The fee is a financing cost, not an extra item purchased from the merchant.
Which account can make the repayments?
PayPal’s repayment-method guidance says Pay Monthly accepts a confirmed bank account or debit card; one-time payments may also use PayPal Balance. Credit and prepaid cards aren’t accepted.
It also says changing a payment method in the Wallet doesn’t automatically change the method selected for that loan’s autopay. The loan-specific selection matters.
Thus, “my new card is in the wallet” and “this loan will debit that card” are different statements. Identify the method recorded for the particular loan rather than treating the wallet’s contents as confirmation. This is a document check, not an instruction to change an account setting. For example, a wallet record naming card A and a loan record naming card B don’t resolve into one instruction merely because both records belong to the same customer.
What can another lender see?
Affirm’s October 23, 2026 update says lenders can access BNPL repayment summaries and may use them in credit decisions. It says these new summaries don’t currently affect FICO or VantageScore scores; certain monthly loans originated before April 1, 2025 remain visible and may affect FICO scores.
Use that dated update, not the older “other lenders cannot see” paragraphs retained below it. Visibility to a lender and inclusion in a particular score are different questions. Neither establishes how a specific lender will decide your application. These are Affirm’s stated distinctions, not a forecast of every provider’s reporting or future scoring practices.
Could the payment account add a cost?
The Federal Reserve’s August 2026 discussion identifies overdraft and insufficient-funds fees as possible consequences when the linked account lacks enough money for an installment. These are separate from the financing provider’s charges.
Its analysis uses the 2025 Survey of Household Economics and Decisionmaking: 11% of BNPL users reported a payment triggering an overdraft or insufficient-funds fee in the prior year. That’s a survey result, not your probability of a fee or a rule that every failed payment costs money.
When reading an offer’s “no late fees” wording, keep the payment account’s terms in view. The lender’s fee statement alone doesn’t describe what the bank may charge.
What starts the repayment clock?
PayPal’s Pay Monthly explanation says the first payment is due one month after the merchant processes the order. The agreement assumes same-day processing; delayed processing can produce an updated schedule. Due dates can’t simply be changed by the customer.
For items processed or shipped separately, interest begins when the first item is processed or shipped. Later items update the balance and may change the payment amount, prompting a schedule.
For split shipments, compare the updated notice with the order entries. An earlier checkout estimate may not describe the current repayment timetable.

Parent Pays Student Loan Interest: Who Deducts?
Separate payment and obligation.

Returned Loan Debit: Two Fees?
Trace the payment and fees.

Rehabilitation Payment Too High?
Check an alternative request.