Child Interest: Comparing Tax Calculations
Reconcile the parental tax increment.
Estimated reading time: 1 minute
A child’s investment income can require a parental-tax comparison, not simply the child’s own bracket.
Fictional 2025 case: a single U.S.-citizen dependent is 16 at year-end, has only $10,000 taxable bank interest, does not itemize and must file. Verified taxable income is $8,650. Both living parents file jointly with $50,000 ordinary taxable income. They make no election to report the child’s interest themselves. No other child, preferential-rate income, foreign exclusion, special tax computation or adjustment applies; all use calendar years.
Form 8615 gives net unearned income of the smaller of $10,000−$2,700=$7,300 and $8,650: $7,300.
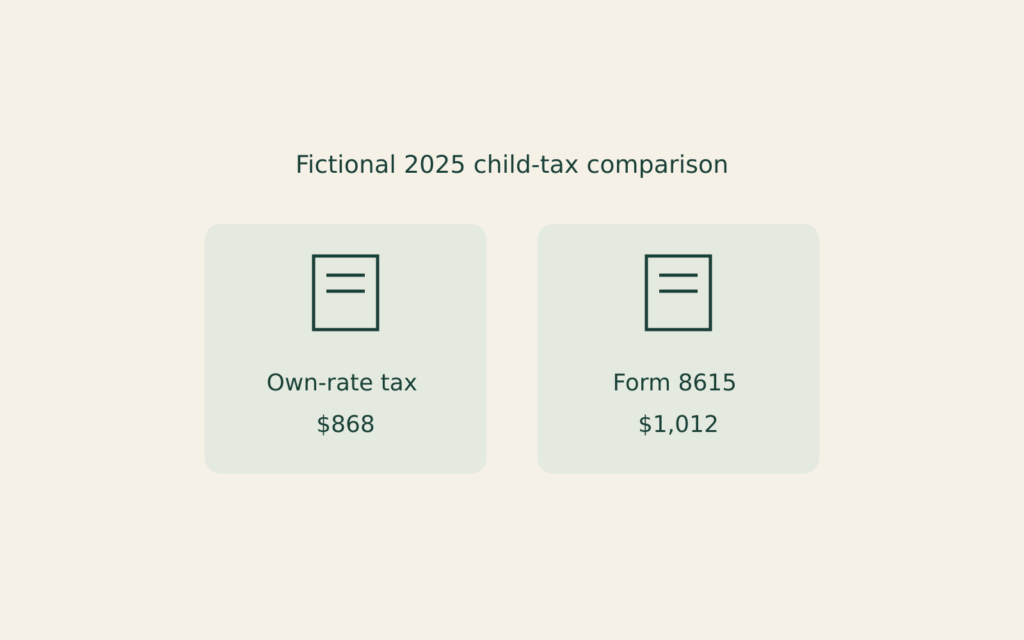
The 2025 Tax Table gives joint tax of $6,402 on $57,300 versus $5,526 on $50,000: an $876 increment. The child’s remaining $1,350 taxable income produces $136 single-filer tax, totaling $1,012.
Compare that with $868 single-filer tax on the full $8,650. Form 8615 selects the larger $1,012—not the final balance after credits, withholding and other taxes.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.